Saturday, October 24, 2015

Restaurant Dining

Eating at restaurants should be a fun social activity, not a chance to refuel.


As I have noted in other postings, eating out in restaurants several nights a week (or for lunch every day) is one way to go broke and ratchet up credit card debt.   When I say this, people get reactionary (and I hate that) and say things like, "Well, you gotta have fun once in a while!"

Once in a while, yes, every damn day, no.   There are people in this country with gourmet kitchens with high-end appliances and whatnot, and inside their subzero refrigerator is nothing but three moldy Styrofoam clamshells that they brought home from a restaurant the night before.

And if you ask them, they are "too busy to cook!" but not too busy to spend four hours every night in front of the television, or an hour every day driving to work.    The reality is, it is a habit, and a nasty one.  We get comfortable having someone else prepare our food, and since we don't eat proper snacks between meals, we are not "too tired" to cook, but "too hungry" and want instant gratification.

So we order out or go out to dinner - or lunch - and run up more debt and then get fat and pay a personal trainer to help us work it all off.  It is an idiotic way to go through life.

Eating out can be a lot of fun, but it can also be a huge cause of credit card debt.   Many Americans eat dinner out five nights a week or more, plus lunches and breakfasts, and as a result run up huge credit card debts over time.  Like the lady in a recent posting, they act bewildered as to "where all the money went."

Again, this is not to say you should never eat out, only that it should be a fun special experience, not merely a chance to refuel your stomach.    And you can eat out once in a while (like once a week) and not spend a lot of money.    As I noted in an earlier posting, restaurant meals can cost four times as much as a meal made at home.  The amount of savings here isn't trivial.

But it isn't hard to go to a nice restaurant and spend $100 on a meal for two people, with a bottle of wine.   Such meals are fine for once-in-a-while, but a middle-class person can't afford to eat that way every night - nor can their waistline!

1.  DON'T use a restaurant as a kitchen:  Dining out should be a special occasion, not a chance to refuel yourself.   Make a habit of preparing your own meals 80% of the time, at least.

2.  Let's Do Lunch:   In most restaurants, breakfast is the cheapest meal, followed by lunch and then dinner, which is twice as expensive as lunch.   If you are dining out on vacation, for example, try doing lunch instead of dinner, as it will be a lot cheaper.  If you are in New Orleans, for example, there are a lot of very fine restaurants - that are very expensive to visit for dinner.  For lunch, though, the same food is often half-price.  Experience the cuisine and the ambiance, at half the cost!

3.  Avoid the Expense Account Restaurants:   Hotels and Convention Centers cater to business people on expense accounts.   Expensive "chop houses" with their mammoth steaks and $18 baked potatoes (I kid you not) are fine when you are spending the company's money on client entertainment (but even that is not fully deductible!).   Such places don't cater to ordinary folks like us, and are prohibitively expensive.  It just doesn't make sense to eat at place designed for folks on expense accounts (unless that $18 potato is your entree!)

4.  Order Less:  Ordering a pile of food and then taking some of it home in Styrofoam clamshells is not cost-effective.   You are not "saving money" by bringing some food poisoning nightmare to work the next day as lunch.  Order an appetizer as an entree, or split an entree.   Just because the menu has appetizers, soups, salads, entrees, and desserts does not mean you have to order one of each.

5.  Explore Early Bird Specials and Prix Fixe:  Yes, the "early bird special" that old people like is often a bargain.   Similarly, prix fixe meals (offering an appetizer, salad, entree, and dessert, often with a glass of wine, for a fixed price) can often be a better deal than ordering a la carte.

6.  Avoid Chain Restaurants:   Getting back to #1 above, most chain restaurants cater to the restaurant-as-kitchen crowd, who want bland, inoffensive and uninteresting foods that you could easily make at home for a lot less money.   A plate of pasta with sauce and bread is not a very interesting meal - nor a difficult one to assemble on your stove in a matter of a few minutes.  And no, "unlimited breadsticks" doesn't make it a bargain.  Moreover, most chain restaurants, even though modestly priced, are no real bargain, in terms of value for the money.   You can go bankrupt, one restaurant meal at a time, and kidding yourself that Chi Chi McGullicuddy's Onion Garden Lobster Buffet is "affordable" is one way to do it.

7.  Specials:  Often specials are not so special.  Sometimes they are an attempt by the kitchen to get rid of a lot of food stock that is about to expire.  Sometimes they are an attempt by the kitchen to expand the menu and offer variety.   Sometimes they are bargain-priced items.  Other times, they are often the most expensive item on the menu.  Many people bite on a "special" because it is the last thing that sticks in their mind when the server comes to take an order.   But think about them carefully, particularly when the server doesn't mention the price.

8.  Look at Prices:   Every restaurant menu has a cheapest item (usually a pasta or chicken dish) and a most expensive item (the surf 'n turf, for example).  Usually neither are ordered very often.  The former may be a bland, flavorless mess that is no real bargain.  The latter is a rarely prepared item and is rarely prepared well.    If you are more than 100 miles from Maine or Florida, chances are the surf 'n turf includes a frozen lobster tail.  Obscenely priced entrees are a doubly bad bargain as not only are they expensive, but since they are rarely ordered, they are often not prepared well.

9.  The Wine List:   Some restaurants provide a phone-book like volume as a wine list.   I generally dislike these.   There is too much to choose from, and many of the wines are horrifically overpriced (such as the $2200 bottle of wine I saw at Antoine's in the French Quarter.  Here's a hint:  If you go there for dinner, eat at the bar, as it is a lot more casual).  Some of these lists are a bad joke, as the proprietor doesn't even stock half the labels, and some labels have been sitting so long they are corked and undrinkable.  Most folks order wines within a fairly narrow price range.   And there is no shame in ordering the cheapest (or second-cheapest) bottle on the menu.  Antoine's, in addition to a $2200 bottle of wine, had a $30 one, which was just fine.  The best restaurants have a compact and interesting wine list that is reasonably priced.

10.   The Wine Up-Sell:  Often the server will suggest a different wine, usually a more expensive one.  If it is only a dollar or two, then maybe it is a genuine recommendation.   However, if it is twice the price - or worse yet, the price is undisclosed - then maybe you should take a pass.   I fell for this once, being talked out of a $28 Pinot Noir and into a $65 one, when the server neglected to mention the price delta.  Another little sneaky trick is to bring you a different bottle than what you ordered.  You order the $30 bottle and they bring you a $50 bottle, and if you didn't pay too much attention to the name, you may say, "That's fine" and not realize you've been stealth upsold.  And yes, this has happened to me as well, on more than one occasion.

11. Dessert:  Great desserts are worthwhile, but few at most restaurants are truly great.   A server comes to your table and makes Cherries Jubilee or Bananas Foster, complete with a fiery show, and it is fantastic.  Other times, I have had  plates of melting mush brought to me from the kitchen, and felt gypped out of $10.   If they make their own pies and cakes, maybe it is worthwhile - but it is also very rare to find this.   Desserts are a huge mark-up item for most restaurants and servers are taught to sell, sell, sell, the upgrade.   Problem is, most restaurants don't even make their own desserts but instead order them from a local bakery or the like (act shocked).   So you pay $12 for a piece of a cake or a pie that the restaurant paid.... $12 for.   And it isn't even fresh half the time.

* * *
Some non-economic restaurant tips:

Many people love to complain on Yelp about service at a restaurant, and most of these people never worked in a restaurant and thus have no clue what is going on.  If you go to a busy restaurant during peak serving time and then make a bunch of special requests, well, you're going to be giving out one-star Yelp reviews and it's your fault, not theirs.

1.  Off Hours Dining:   Eating early or late at any popular restaurant means getting the table you want and good service.   And often this means shifting your meal time by as little as a half-hour.   You go to a restaurant and there is a line out the door at 6:30.   At 7:30 half the tables are empty.   When would you prefer to dine?   There are some caveats, of course.  If you go for the "early bird special" the staff may be distracted and disorganized due to set-up issues.   Going late may mean some menu items are sold out.  But overall, less crowded is better.

2.  Bottle of Wine, Pitcher of Beer:   At a busy restaurant, consider ordering all of your drinks at once, by ordering  a bottle or wine or a pitcher of beer for the table.   You never have to wait for a refill on your drink this way.   It amazes me that some folks in a party of four cannot agree on the same beverage, but insist on all having different drinks - one orders a martini, another a lite beer, a third a glass of house wine, and the fourth a frozen strawberry margarita.   For the cost of four shit drinks, you can have a nice bottle of wine.   And martinis and margaritas are not usually drinks one serves with a meal -  if you have any taste at all that is (exception, maybe some Mexican joints, a margarita might be in order, but frankly, a good Mexican beer is a better choice.   So many Americans order lite beer.  How sad).

3.  Order All At Once:   In the restaurant business, you may see two or three people before you even see your server.   A maitre d' greets you at the door, and hands you off to someone who leads you to a table and perhaps hands you menus.  Someone else comes and brings you water and says, "your server will be here shortly".   The server then takes a drink order and then comes back with drinks, and then leaves again and comes back later for food orders.   You can literally wait a half-hour before you even order.  If the restaurant is busy, you may wait another half-hour for your food.   An hour goes by and now your blood sugar is reaching Yelp one-star low.  Read the menu and save the chit-chat for later and get your order in early.   You can enjoy talking over drinks while you wait for your food.

4.  Don't Be Afraid to Leave:   Some restaurants are dysfunctional.  One or more of the servers, busboys, cooks, or whoever is stoned out of their mind (drugs are a big problem in the restaurant business) or they just can't get it together for other reasons.   For example, I related how we once went to Red Lobster out of curiosity - after someone had given us a gift card.  No one ever waited on us, so we left.    If you are sitting at a table and no one comes to take your order or even bring you menus, you've been "forgotten" and chances are, that means the restaurant has some service issues.   If you detect these sort of problems early on (e.g., other people at adjacent tables complaining, harried staff, disappearing staff, etc.) it is probably best to cut your losses and move on.  Trying to make a bad deal into a good deal never works.  

Some people try to do the opposite - they snap their fingers and complain to the manger, convinced they can "fix" the restaurant and get better service.  It rarely works.  Just stop patronizing the place and let it go out of business.  Or maybe realize the problem is you, not them.   A friend of mine keeps going to the same restaurant every week, and then complaining that the service is poor.   They badger the help and complain to the manager, convinced they are going to get better service - or maybe a free meal.   It never works, they are never happy.   Dine someplace else.

By the way, I bought stock in Darden, and since it shed Red Lobster the stock has gone up about 30% and it pays a dividend of 3.44%.  All the financial press was writing the epitaph of the company, because stories like that sell newspapers and generate click-through revenue.

5. Don't Make a Nuisance of Yourself:   Making special orders and special requests, particularly during the peak dinner rush is one sure way to make yourself unpopular and also end up disappointed, when the chef doesn't prepare the food according to your complicated instructions.   Another friend likes to order chicken wings, but "no drumsticks" which is an odd thing, and hard to do, since they come out a five pound bag (you are asking the cook to hand-sort the wings, basically).   The server makes some verbal request to the cook, but since it is busy, he forgets, and my friend gets pissed-off.  A better approach would be to maybe share the order with a friend who likes the drumsticks, perhaps.

You don't have a "right" to change ingredients on a menu.  And no, chances are, you are not lactose intolerant, or require a gluten-free diet, or whatever.  It is just some magazine article you read.  Going to a restaurant and expecting them to cater to your every need is unrealistic.   And restaurants that try to pander to such customers are usually not very good restaurants.*   Trying to order Vegan at the chophouse is just stupid, really.    Either learn to live with what they are serving, or dine somewhere that serves what you want.   People who claim to have special food needs or desires are often just being passive-aggressive and are trying to get attention.

Now again, some extremist will say, "Well what about food allergies?"   I have two friends who have very real food allergies (as opposed to say, helicopter Moms who diagnose imaginary allergies in their kids).  One is to peanuts, the other to shellfish.   They carry epi-pens with them at all times, as they have had near-death experiences due to these allergies.   Their situation is far different than the idiot who reads something in the paper about glutens and then decides they are allergic to them through self-diagnosis.

And sadly, the fake allergy people screw things up for the real allergy people.   Because so many folks claim to have afflictions today, some restaurants don't take seriously claims by patrons that they are severely allergic to some food items. 

And when it comes to food preferences just order something else.   Mark had a lady order the garlic chicken one day, "but could you make it without the garlic?"    In other words, she wanted a grilled breast of bland, flavorless chicken.   He brought her one and she was ecstatic.

In other situations, people like her end up screwing up the menu.   A fine Tapas place in Old Town went out of business after they catered to the bland crowd.   The garlic spinach was reduced to a bland mass of watery spinach after one customer complained "there was too much garlic" in it.   They dumbed-down the food to satisfy one loudmouth jackass who knew nothing about food and had no taste.   Before the year was out, they were out of business.  There is a lesson there for restaurateurs.  The customer isn't always right, and if you pander to the customer too much, you end up losing business, not gaining it.  The best restaurants have a line out the door and treat you as though it were a privilege to eat there - which it often is.

But regardless, if you make special requests and special orders, don't be upset, surprised, or disappointed when the result is less than expected or takes a whole long longer to prepare.  Most restaurants are set up to make certain things in mass quantities, particularly when the rush is on.   Expecting custom-made cuisine is just not reasonable.


*  When I go to a restaurant and they have each item on the menu identified with a panoply of symbols for "Gluten Free" or "Vegan" or whatnot,  I know that it is not going to be a very good restaurant.  They are pandering to the crowd.   The best restaurants don't have to do that - and they don't.

* * *

This is not to say you should never order some of these things or never go out to eat.   Again, I hate it when people twist my words around and say idiotic things like "Well, I don't want to live on beans!" - as if dining out at Chez Paul and eating a leftover can of beans are the only two options in life.

These are just hints and suggestions and ideas to think about.   A restaurant meal can be a lot of fun, once in a while.   And it need not bankrupt you, either.

Friday, October 23, 2015

Financial Discipline Requires.... Discipline

In order to be financially independent, you have to discipline yourself.  If you don't, others will do it for you, such as banks and credit card companies - or the government.


In my previous posting, I may have come across as a little hash, but the OP on reddit asked for harsh truths and someone to "tell her what to do".   Sadly, the financial "advice" on Reddit was to get a new job to make more money, or get a special super-duper credit card.  In other words, work harder and pay more interest.   Who posts this crap?  Trolls for the banks?

But the real answer is that there are no easy answers.  And that unfortunately is not what people want to hear.  They want "one trick of the tiny belly" or "these easy steps to be debt-free!" or "you can retire on $7,000 a year!"

These answers are not answers at all, and are in fact harmful to people, as they suggest that financial discipline is "easy" and if you are screwing it all up, then you must be an imbecile.

It isn't easy, but it isn't hard, either - certainly not impossible.

When I was 25, I was like the young lady in the scenario (not the one above!).   I spent money freely and wondered "where it all went" every month.  If I had a dollar in my pocket, I spent a dollar.   I was working at a $4.25 an hour job and spending $6 every day on lunch.   Do the math on that - the first two hours of the day were spend paying for lunch.   Two more hours - at least - for my transportation.   Very little is left over for me, at the end of the day.

The discipline I didn't have was tracking my spending.  Oh sure, like the lady in the previous posting, I could track the major big-ticket items my life, like my student loans, credit card bills, rent payment, car insurance, and car payment.  But the rest?  It all just evaporated.

Once I started tracking and budgeting every damn expense I had I realized where the money was going - all over the place.

For example, it is tempting to think that if your car insurance is $240 a month and your car loan is $190 a month (more for insurance than the loan!  Very typical of that age.) that your car is costing you about $500 a month with gas, or about $6,000 a year.   But as I noted in another posting, the real cost - when you calculate from a net worth perspective - can be a lot higher.

It is not that money is being wasted all in one place, but that it is leaking out every which-a-way.  And unless you start tracking these things, you have no clue where you are going or where your money is going.

I recounted in another posting a friend of mine who told me I needed to "cut out the waste" in my business, but as I explained to him, there was no pie-shaped wedge in Quickbooks labeled "waste".   He had similar opinions about the Federal Government - that a quick click on "delete waste" was all that was needed.   Not surprisingly, he was a tax protester and got into trouble with the tax authorities.

Today, I log every transaction I make on Quickbooks.  I check the balance on my credit cards (one for personal, one for business) as well as my bank balances (checking, savings, business checking) on a daily basis an then reconcile the amounts with Quickbooks.   Each expense is categorized, so I can see where the money is going.

Is this a pain in the ass?  Not really.  It takes about five minutes to do. Yea, sure, there are "easier" solutions like Mint, but that application really doesn't track very well (as it only uses credit card codes to determine what you are spending money on).   Again, easy solutions are not usually the best ones.

Why do I do this pain-in-the-ass method of tracking spending?   Well, to begin with, it isn't as much of a pain-in-the-ass as you might think.   It doesn't take but a few minutes a day to balance the books.    But more importantly, I know, down to the penny, how much money I have in the bank,  how much is available, and what I am spending it on.   You literally cannot bounce a check, ever, if you use a technique like this.

Similarly, by checking the credit card balance daily (and logging charges and reconciling them) I can track my credit card balance and realize where I am going with my spending.   It is a lot harder to get into credit card debt trouble when you track expenses daily.   When you log on and realize you over-spent the day before, it motivates you to be more careful next time.

Financial discipline takes another form as well - cheapness.   In my 20's and 30's and even 40's, I never looked at the price of items in the grocery store, or on a menu, or at a bar.   I bought what I thought were the best quality goods and only little people cared about price.   In the scenario provided by our 25-year-old in the previous posting, she admitted she spent a lot on expensive "healthy" foods as she wants to "lose weight".   But of course, losing weight is akin to losing credit card debt - you just have to stop spending and pay down the debt (eat less and exercise more!).   Buying expensive foods isn't going to help you lose weight.

And yes, there is a middle ground between "Raman Noodles" and gourmet cuisine.  Whenever I mention cutting back on spending, some jackass 20-something will say, "Well, I'm not going to live on Raman Noodles!" as if that was the only way in the world to save on expenses.   It is a straw-man argument of the worst sort.  It is also a self-justification for spending, just as "I need a reliable car to get to work!" is a self-justification for buying new cars all the time.

Today, I look at the prices of everything.   This is not to say I never spend money on stuff, only that I think about what I am spending it on.

For example, in a recent posting, I noted we spend the afternoon at the Hilton on the Riverwalk in San Antonio, having a bottle of Champagne and street tacos.   This may sound extravagant, but a bottle of wine is often cheaper than buying it by the glass, and a inexpensive Spanish Cava can be had for about $30 a bottle, even at the Hilton.   Buying top-shelf liquors and ordering large entrees, on the other hand (and taking home "leftovers" in a Styrofoam clamshell) would cost four times as much, and be far less satisfying (overeating never leaves me feel satisfied, just bloated).

So I look at prices.  Of food, of wine, of menu items.   Lunch at a fine restaurant can cost half the price of dinner.  Same good food and fine atmosphere, for a lot less money.   A lot of "brand name" things in the grocery store are no better and sometimes worse than store brands.  And a lot of things can be bought at the dollar store, leaving you more income for savings - and for doing more with your money.   I don't mind spending less if I end up getting more.

For women, it is doubly difficult to cut back on spending.  First, I think there is a nest-building, nuts-and-berries gathering instinct that perhaps is bred into women from our ancestry long ago.   Women love to shop, far more than men.    Second, women have to spend a lot of money on hair, makeup, and clothing - all expenses that for men, are very minimal.  I can cut my own hair with a $20 pair of clippers.   For a woman, this is not realistic - at least with today's societal norms.  And let's not get started on perms and hair extensions.   The poorest of women, it seems, spend the most on hair, as Chris Rock noted.

Women's clothing goes in and out of style yearly, while men's clothing is "classic" and styles last for decades before it becomes "retro".  And let's not get started on shoes.   A man can make do with a few pairs of sturdy shoes, boots, and sneakers.  Women pay top dollar for flimsy designer shoes that are wildly uncomfortable and end up causing foot and back problems.

Even something as mundane as laundry is more expensive for women.  As one of professor Banzhaf's students found out, the cost of dry cleaning a woman's shirt is 20-50% more than a man's - with no real basis for the difference in price.  So I can understand, somewhat, how for a woman such as in the scenario in my previous posting, cutting back on expenses can be hard.

Hard - but not impossible.

Financial discipline also means saying "no" a lot, to come-on offers, credit card offers, and things that seem "too good to be true!"   You will be pummeled by credit card offers in the mail and online.   If you take each one of these offers, you will end up with a wallet of credit cards and a world of woe.   Similarly, pitches for online "ebates" or whatever are not going to "make you money" as you cannot spend your way to wealth.

It is tempting to think that maybe that 1% or 3% you are getting back on your gas or food charges will make the difference in your life.   But if it means paying 15% interest - or even 7% - then you are coming out behind.

It takes a lot of courage - discipline - to say, "thanks but no thanks" to the carnival of spending offers that is shot at you like from a firehose on a daily basis.   And one way to achieve this discipline is to watch less media.   The media presents poor normative cues all the time, pitching such ideas as "rewards cards" and serial refinancing, and even payday loans and check cashing stores.    And let's not forget ideas like using restaurants as a kitchen, or "you're too tired to cook, order a pizza!"

The real discipline is to believe in yourself and those inner voices that say, "this is all a carnival of shill and scam artists out to get at my pocketbook!"   It takes courage to go against the flow, against what most of society does and practices.

It takes discipline.   And it isn't easy, it is very hard, and it never, ever ends until you are dead.

***

A reader writes:  Regarding discipline, I've heard "You can't manage what you don't measure."

That sort of sums it up in one sentence.   Once you track spending - every damn penny of it - you realize how much you are spending on certain things and know "where all the money is going" and where you can cut back.

Wednesday, October 21, 2015

Zero Fault Tolerance


Maybe it is a product of our modern society, but today, no one is forgiving of anything it seems - with disastrous results.  Not all of us disarm bombs for a living!

In an era not too long ago, mistakes were tolerated more freely.   It was expected that things would get messed up, as it is part of the human experience.  And as a result, we built into most human-made systems, ways to correct or repair errors.

Our Constitution, for example, anticipates that changes would be needed over time.   Today, if there is one typographical error in Obamacare, people call for its repeal.

Similarly, with many companies and organizations today, there is an insane insistence that everything be done perfectly the first time, with no margin for error.   Assembly lines run on a "just in time" inventory system, so if one nut or bolt is out of place, an entire factory shuts down.   Small airplanes and trucks stand by to rush in parts at the last minute, if something goes wrong.

Similarly in the business world - and particularly the legal one - there is no margin for mistake.   One mistake is all it takes to end a career in business.   In the medical field especially.   And if you make even one small mistake, an army of lawyers will pounce on you and sue you out of business.

In the entertainment world and politics (the same thing, I guess), all it takes today is one mis-step or one poorly worded statement, and you are out of a job - or out of office.   Make what seems to be a racist tweet, and it's all over.

Today we have "zero tolerance" policies in school, which expel students if they make even one small mistake due to youthful exuberance.   In our criminal system, mandatory minimum sentences and "three strikes" laws leave no room for real justice to be done.

For young people starting out, this zero tolerance policy has ended many a career before it has begun.   Bad credit?   Poor Grades?   Late on your student loans?   Failed a drug test?   Got arrested?   Failed the background check?   Too bad for you, buddy.  Maybe there is a job for you at a tattoo parlor or something.

Is this a good thing for humanity?   This take-no-prisoners approach to life?   I think not, and for several reasons.

First of all, it cranks up the stress level on everyone.   At home, at work, online, or whatever, we all walk on eggs all the time, fearful of even one screwup.   Post something online with a mis-spelled word, and 20 people will jump down your throat to point it out.   Have a bad day at the restaurant?   Yelp will have you out of business by the end of the day.

No one is allowed to strike out any more.  No one is allowed to make a mistake.  No one is allowed to be human.   And time was, we expected people to make mistakes.  In Baseball, striking out half the time is considered a pretty darn good record, not a dismal example of failure.   And yet in sports metaphors, we are told "failure is not an option."   But it is - a predictable outcome for one team, in every meet.

But this sort of zero-tolerance practice has an even more insidious effect on our society.   In a society that does not tolerate error at any level, people become so fearful of making an error that when caught, they will try to "bury" their mistakes.   This usually means that their mistake will be compounded, catastrophically.   A simple leak in a pipeline becomes a reactor meltdown.

I ran into this effect recently trying to title my car.  The lady at the car dealer was supposed to handle the title and tags.  She screwed up both.   I ended up getting the tags myself as a favor to her - but of course, she didn't see it that way.  It was the DMV's fault or someone else's, not hers.   Rather than own up to the error and say, "Gee, I'm sorry" she acted like I caused the problem.

On the way back from the DMV, I realized to my horror that she had titled the car in the wrong name - she left Mark off the title.   So I called back and once again got the blame game turnaround.  Nothing could be her fault, as if it was, then she would get blamed for it.   So instead of a "I'm sorry, I'll fix that right up for you!" she tried to bury the mistake by saying I had to live with it.  This way, she hoped, I would just meekly go away and no one would ever find out she made an error.

Well, of course, that wasn't going to happen.   I wasn't going to live with a mis-titled car.   So I had to escalate the matter, and now her boss knows about it, and rather than sweeping it under the rug, the entire thing has blown up in her face, which she should have realized would have happened.   And it all could have been avoided by simply admitting the mistake and then fixing it.

We all make mistakes.  I had a similar problem with a Patent recently.   I mistakenly assigned the rights to one Patent to one organization, when it should have been assigned to two.   Now arguably, I could have blamed the client for not being clearer about the matter.  But rather than play the blame game, it is a lot easier and more effective to say, "Gee, sorry about that, I'll fix it right up for you!"

And it really isn't hard to fix - just some documents to be signed and filed.   It takes a few minutes, really.   And the same is true for car titles.   In the history of motor vehicles, I am not the first person to have a typo error or other problem with a title.   There is a way to fix these things.

(Sadly, in the Patent business, fewer and fewer things can be fixed.  When I started in this practice nearly 30 years ago, almost anything could be fixed with an amendment or a petition and a "my bad" and a small fee.   Today, there are many aspect of this business which have zero-tolerance characteristics.   You mess up something today, and it literally may cost you your career.   I yearn for retirement as a result).

But in an organization that tolerates zero errors, well, people get paranoid and do weird things.  They deny reality.  They bury their mistakes.  They hide malfeasance.  And these things, when hidden cause greater problems down the road.

Zero tolerance for error is probably what sunk the Germans in World War II and the Russians in the cold war.  When you realize the penalty for error is being stood in front of a firing squad, you either take no risks at all, or spend your entire day documenting and double-checking things, so you can blame others when things go wrong.

Perhaps it is our increased reliance on electronic communications that has fueled this trend.   We expect instant gratification today, and everything has to be perfect from the get-go, or we turn to social media to vent our frustrations.

But it needn't be that way.   Yes, the guy disarming bombs has a zero tolerance environment to work in.  On the other hand, if he fails, the consequences are all on him.   A surgeon has a near-zero tolerance environment to work in as well.   And in the past, many a doctor buried his mistakes and we accepted this as part and parcel of a medical system as we were just glad that there was a possibility of being healed.   Today?   One mistake and your malpractice premiums will go so high as to drive you out of business.   We are no longer a forgiving society.

But this fails to explain why we have taken so many other areas of our lives and made them subject to such draconian consequences.   Why do parents go and scream at a school principal when their kid gets a "C" in third grade?   Why are parents convinced that getting into the right pre-school in Manhattan is a precursor for success at Harvard?  Why do we have "Tiger Moms" and "Helicopter Parents"?

It really makes no sense at all.  We are placing artificial pressures on ourselves, for no reason whatsoever, other than to crank up our own stress levels and degrade our own quality of living.

Let's bring back the do-over, the apology, and mistakes were made.  Rather than calling for someone's head every time something goes wrong, maybe it would be more constructive to fix the problem and get to the root of what caused it - and provide a mechanism to fix similar problems in the future.

Maybe this is a crazy idea.  Maybe it would be better if we all became fault-free robots marching in lock-step.   Maybe not.

How Credit Cards Erode Your Life

To a young person, having a lot of credit cards means you are financially successful.   When they get into financial trouble, their blinders prevent them from seeing that credit cards are actually the problem.


On reddit the other day, was this plea from a young woman who couldn't figure out where all the money was going.   But if you read her detailed scenario, one thing jumps right out at you.   She has an awful lot of credit cards and other loan debts, for a young person:


Long story short. I am a 25 year old female who is continually struggling with money and debt even though I now work two jobs, both above minimum wage, and I can’t really figure out why. Looking for some tough love and harsh truths, right down to people telling me exactly what to do here.
Below I have outlined my debts as well as my bills, and my estimated earnings for both jobs. Both are hourly so they can vary depending on clock in/clock out times, but rarely by much. Neither have opportunity for overtime. Both are new jobs, Job 1 I’ve been at since the middle of September and Job 2 since about two weeks after that. Before that I was laid off for 2.5 months which is where the spiral into money issues really took its toll. It’s no excuse, I should have been better. I know better. Though I will say that 2/3 of the AMEX debt was a very expensive dental surgery I needed that couldn’t be avoided.
I currently have less than $200 cash to my name. No savings re-built yet from when I depleted it during my layoff.
——
Job 1: 40 hours/week @ $15.50/hr = $944 biweekly after tax
Job 2: 18 hours/week @ $8.25/hr = $232 biweekly after tax
Total: $1176 biweekly, ish.


$$ Debt
$11,000 Student Loans
5,831 Auto Loan
3,970 American Express Blue Cash Preferred Credit Card †
1,219 Huntington National Bank Voice Credit Card
999 Barclaycard Sallie Mae Credit Card †
960 Personal Loan
973 Credit Union “Flex” Credit Line **
$24,952 Total
† These cards have no interest until April
** This has no interest at all
——

$$ Bills
$230 Car Insurance
190 Car Loan Payment
160 Healthcare and Dental
100 Treasury Collections†
100 Personal Loan Payment
65 Student Loan Minimum Payment
50 Huntington CC Payment‡
50 AMEX CC Payment‡
50 Barclaycard CC Payment‡
40 Electric Bill
36 Internet Bill
30 FlexLine Payment Minimum
26 Frivolous Monthly Things
20 Gym Membership
$1147Total


(The first thing you notice about this scenario is how everything is chopped up into weekly, bi-weekly, and monthly numbers, making it hard to parse.   According to her numbers, she is making $39,962 a year in gross income (not bad) and taking home $30,576, or $2548 a month.  Her expenses are $1147, leaving $1401 in disposable income!)

If you look at her situation, she does not have a staggering amount of student loan debt (whose interest is deductible, and is a long-term investment, hopefully, if she got a worthwhile degree).   Even the auto loan debt is pretty small, although having a car loan when young is problematic, as it means paying exorbitant insurance rates.  $230 a month for car insurance is more than what I pay a year for basic liability, or at about for 6-9 month's coverage if I want collision.   How much you wanna bet she has a low deductible, with towing and rental car coverage, as well as uninsured motorists and medical?  Again, this is typical among young people - they take the quote offered by the friendly local agent and don't question it.  I would suggest GEICO, online, where you can see what coverage you are paying for, and how much each aspect costs.

But the real deal is three credit cards, a "personal loan" and a "flex credit line".   You cannot borrow your way to wealth and debt is anti-wealth.   It seems like a pretty simple proposition, really.  You borrow a dollar, you have to pay back a $1.20 at credit card interest rates.   Perhaps even $2, as the interest is "revolving".   So when you borrow money, you are making yourself poorer, as you now have less money to spend or save every month.

Fortunately, the solution here is pretty simpleCut up the credit cards.   Keep the lowest interest rate card and discard the rest.   And no, miles are rewards don't compensate for the cost of all that interest she is paying.   If you are carrying a balance, even for one month of the year, chances are the interest is wiping out any 1-3% "savings" with a reward card.  They throw pennies at us, hoping we spend dollars.

Similarly, she should pay off the "flex line" and close the account, as well as the "personal loan".   Granted, this may take a few months, but the money she might save by switching to GEICO and dumping junk coverage might help pay for this.  Why close a "flex line" of credit?  Because it is a temptation to borrow, and borrowed money has to be paid back.   The fewer sources of immediate credit you have in your life, the less likely you are to borrow.

Of course, if you read her plea carefully, you realize she has $1401 a month in leftover money - more than half her income.   And she says she pays no rent.  Obviously, there is a $1401 hole in her budget here that she doesn't want to talk about for some reason.   Partying?  Dining out?   Drinks at the club?   Clothing?  What?  The silence is telling.

The bulk of the credit card debt was for an AMEX card for "very expensive dental surgery" she needed.  I certainly hope she got a second opinion on that, as dentists, as I have noted before, often suggest expensive work that is not really needed, and then suggest financing it.  Chain dental stores are the worst at this sort of thing - and yes, they do target the young and naive - particularly young people with dental insurance (as she claims to have).

When you are younger, what a man in a white lab coat says often seems like the word of God himself - particularly when you are lying prone and have a lot of cotton and instruments in your mouth.   Many of us are not trained to be skeptical of doctors and dentists, and it is only when you get older and realize that many of them are just schmucks like you and me - and many of them are quite incompetent as well - that you start to question these things.

Fortunately, this young woman isn't quite in a pickle just yet.  Her debt load is equal to about a 2/3 year's income at this point - after tax (she is taking home 30,576 a year!) and that also means her debt service is less than 1/5 of her income, which is not considered onerous by the banks, at least, who view 1/3 as the stress point.

Note also, the amounts shown for the card payments are clearly the minimum amounts due.  If you make a $50 a month card payment on a $4000 AMEX debt, it will take you forever to pay it off!

She just needs to make different choices and change her mentality.  Stop looking at debt as the answer to all problems.  Stop looking at credit cards as a sign of wealth.   Challenge authorities - the dentist, the insurance agent - and don't take it for granted that you need thousands of dollars in dental surgery or to pay thousands of dollars to insure a $5000 car.

And stop looking at life in terms of monthly income and monthly payments.   Note how her entire financial "picture" is couched in those terms - how much I make a bi-week and how much I have to spend per month.   She is not looking at the overall net worth picture which is understandable, as from what I can see, her current net worth is about -$20,000 (assuming the car is worth five grand).   Net worth is your real financial altimeter - telling you how far about the ground you are.   Until you figure out your net worth - on a monthly basis at least - you really can't tell if you are climbing or spiraling into the ground.

When you borrow a dollar, you make yourself a dollar poorer.   It is as simple as that.   If you find yourself constantly having to borrow money, chances are, you are living beyond your means.   Borrowing more money to continue the scheme just makes no sense at all.

And what is really appalling to me, is that this young lady, at age 25, is making good money.   It is sad that a single person, making that much money, has no savings at all.  Kind of hard to feel sorry for that!

We all make choices in life.   And her situation is one of poor choices, in every sense of the word.  She is not a victim of circumstance in any sense.

* * *

NOTE:  Speaking of normative cues, I am sure this young woman gets "a starbucks" every day and tosses the "barista" a huge tip and thinks nothing of it.  After all, "everyone does it" right?   Everyone else is broke, too.  No one wants to think that "trivial" thinks like fast-food lunches and designer coffees are making them broke, but in truth, they are.

Tuesday, October 20, 2015

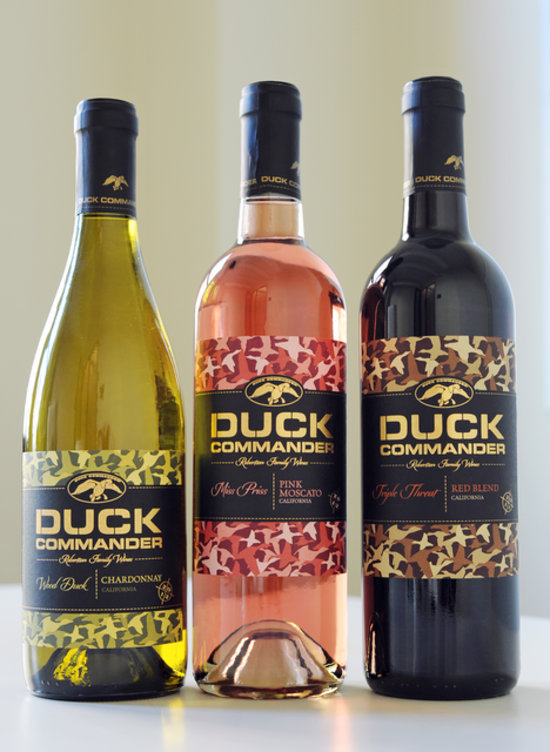
Duck Commander Wine - How Wal-Mart Got Into Trouble

Wal-Mart's temporary troubles can be traced to half-assed buying decisions, like Duck Commander wine.  A complex, overwrought and inauthentic wine, heavy with intolerance, with notes of misogyny, slight overtones of racism, and a heavy homophobic finish.  Leaves a bad aftertaste.  37 points on Wine Speculator.

Traveling across country, we've had a chance to visit a lot of Wal-Marts.  For the RVer, they can be handy, as you can get a new tire for your trailer, or a new battery for your car, while buying groceries, gas, and RV supplies (many have a large selection) as well as beer and wine and sometimes even liquor - as well as propane.  Some RVers even sleep overnight in the parking lots.  We've seen all different kinds of Wal-Marts, from immaculately maintained stores in small towns, to run-down "ghetto" Wal-Marts in the big city.

One puzzling aspect of Wal-Mart is its recent decision to buy a lot of brand-name and celebrity endorsed products.  Traditionally, Wal-Mart always had "the low price, always" which meant that the product selection was limited to generic and non-licensed goods.   If you wanted a brand name product, chances are it wasn't at Wal-Mart.   Instead, Wal-Mart had its own line of inexpensive brands, such as "Old Roy" dog food, Oak Leaf wines, Great Value foods, and whatnot.

As I noted in my Great Value Woven Squares posting, many of these generic store-branded products are a far better value than brand name goods - and value is supposed to be the name of the game at Wal-Mart.   However, the management of the company has decided to move more toward brand-name products and away from store brand, and as a result, there is five feet of shelf space (six tiers high) of Nabisco Triscuit crackers in every flavor, but only one tiny hole in the display with store brand, which is usually sold out.

Is this a good strategy for Wal-Mart?   And are brands that are little more than celebrity product endorsements a good idea?

The Paula Deen episode is a case in point.  (If you can't remember her name, just google "Racist Lady In Savannah" - she is the first hit).   Wal-Mart carried a line of her goods, and then quickly un-carried them, placing them in their "closeout" section along with the rebel flags.   I am not sure her smiling face on a pot or pan sold very many pots or pans.  My personal reaction to product-endorsed lines like this is that the person whose name is going on the product is getting paid to put their name on it, not that they personally selected or manufactured the goods.   I don't take Paula Deen's name on a pan as some sort of endorsement, as compared to say, a brand name.

And besides, I discovered recently that inexpensive pots and pans such as a set made by Tfal and sold at the wholesale club for $89 is a much better deal than even Calphalon.

K-Mart went through similar gyrations with its Martha Stewart Living line of products.  It was an odd match to begin with - upscale Stewart selling endorsed products at decidedly downscale K-Mart.   Once she was arrested, it certainly got awkward.   Today, I doubt anyone cares whether or not their sheets are endorsed by the diva of domesticity.   And besides, 300 thread count is so passe today - with 450 and higher counts now the norm.

Rachel Ray is another example of endorsement that, while it didn't go horribly wrong with a racist rant, tax arrest, or child porn charges, simply failed to move product.  Rachael's smiling face appeared everywhere in Wal-Mart for one season, on everything from housewares, cookware, food, and even dog food.   Today, her line of dog food is the only thing I see left at Wal-Mart.  Her 15 minutes of fame are up, and she wisely cashed in as quickly as possible.   Or was her over-exposure the reason for her sudden downfall?

The Duck Commander/Duck Dynasty crew fall along the same lines.   Suddenly, every single goddamn thing in Wal-Mart has camouflage and "Duck Commander" on it, no matter how ridiculous the connection is.   Duck Commander wine is the most ironic of these, as the Duck Dynasty people, who I am now convinced are just putting on a piece of political theater (much like professional wrestling) have been trying to conceal their hidden yuppie roots for some time.   Selling white wine sort of blows their cover.

But who actually buys this shit?   I rarely see anyone in Wal-Mart wearing a Duck Commander shirt.   Perhaps if I attended more mud bogs, I would see them more often.   I do, however, see them on sale, marked down, and in the closeout section - which tells me that perhaps these endorsed products are not as popular as Wal-Mart thought they would be.

Speaking of closeout section, Wal-Mart has the worst.   If you loiter in these messy aisles (often between the paint and garden sections) you will see a land of lost toys - broken bits, returned things, oddball products, all "marked down" by only 5% or so.  No real bargains to be had there, really.   It is as if Wal-Mart just can't let go of things and mark them down and write them off.   Do they have hoarding disorder?

Other retail chains clear their shelves of unsold goods by marking them down steeply and making them go away - leaving room for products that will actually sell.   Or by returning unsold merchandise to the wholesaler, if possible.

But getting back to the main point, just as McDonald's seems to have lost its way and forgotten its primary mission (fast food, cheap food, served quickly), Wal-Mart seems to have lost its way as well.   Eschewing the "low price" model pioneered by Sam Walton, it has left that market to stores like Dollar Tree which rarely has celebrity endorsed products, but always has the low price, always.   A dollar.

Recently, we have noticed that Wal-Mart appears to have Dollar Tree on its radar, and is offering a limited line of inexpensive bargain items on a back wall, for very low prices.   Perhaps this is only in the test-marketing stage, I am not sure.  I think the idea is to get people to buy products there, while they are shopping at Wal-Mart, rather than make a stop at Dollar Tree first.  

While it is an interesting experiment, it is, once again, an example of Wal-Mart trying to be all things to all people and carry too many lines of goods (do they really need to carry 400 different brands and models of flat-screen televisions? Or is that just for show?).    Selling 79 cent rolls of paper towels isn't undercutting Dollar Tree, it is undercutting their own lines of paper towels.   In other words, they are underselling themselves.  Maybe if the "low price, always" model was brought back and celebrity endorsed products (which are always higher in price) are ditched, sales might pick up.  Just a weird idea, of course, but one that Sam Walton came up with as a winning formula decades ago.

I also think it is a bit condescending on the part of the buyers in Bentonville to stock white-trash celebrity endorsed crap.  I can just hear the voices in the meeting rooms in Bentonville - "But this is what they like to buy" - as if all of the people who shopped at Wal-Mart were like the people of Wal-Mart.  Carrying "Duck Commander" wine makes Wal-Mart a parody of itself, really.  It is as if Wal-Mart just gave up and turned itself into a South Park episode.

Just like Cartman, Wal-Mart seems to be wallowing in its own crapulence.

Does this mean Wal-Mart is going out of business?  Hardly.  Just as McDonald's has somewhat lost its way, Wal-Mart has followed some bad advice and lost track of its founder's vision.    Some of these awkward mistakes will no doubt go away, eventually, and the company get back on track.   Sales are down at Wal-Mart because they no longer sell cheap products, but rather brand-name and celebrity-endorsed products that are not much cheaper than what is sold in other stores.   Once the low prices go away, the compelling reason to shop there evaporates as well.   Particularly when there are other low-cost outlets out there.

I am not sure their present strategy of squeezing suppliers will fix the problem in the long run.   What Wal-Mart shoppers want is low prices, not Rachel Ray crackers, Paula Dean pots, or Duck Commander wine.

* * *


P.S. - How can you quickly tell if a Wal-Mart store is well organized and run?   Go to the bicycle section and see how well the bicycle tubes are organized.   If they are all lined up in neat rows and properly priced, chances are the manager is running a tight ship.  If they are all in a pile falling down onto the floor (as at our local Wal-Mart, always), chances are, you are in a ghetto Wal-Mart.  Another good indicia is to request a propane exchange and see how long it takes them to find the key.   If they trot out there in a minute or two, tight ship.  If you are told that Darnell took the keys with him to lunch, ghetto.

P.P.S. - One of the Duck Commander wines is a Muscato.   Muscato is a soft drink, not a wine.