Saturday, April 24, 2010

The Parable of the Non-Prodigal Son

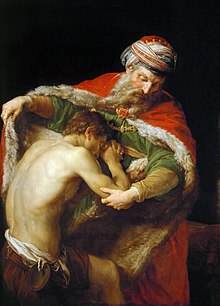
The Prodigal Son Returns.
What a gyp to the Non-Prodigal Son!


You may remember the parable of the Prodigal Son. It is another one of those Bullshit Insane Bible Stories for Crazy People, which, like Jonah in the Whale, makes no sense whatsoever. While the meaning of this story has been debated through the ages, one question remains: What ever happened to the Non-Prodigal Son? That story has never been told, that is, until now.

The original story is found in Luke 15:11-32. Jesus tells the story of a property owner who has two sons. The younger son demands his share of his inheritance while his father is still living, the son goes off to a distant country where he "waste[s] his substance with riotous living" and eventually has to take work as a swineherd. There he comes to his senses and decides to return home and throw himself on his father's mercy, thinking that even if his father does disown him, being one of his servants is still far better than feeding pigs.

But when he returns home, his father greets him with open arms and hardly gives him a chance to express his repentance. He kills a fatted calf to celebrate his return. The older brother resents the favored treatment of his faithless brother and complains of the lack of reward for his own faithfulness. But the father responds: 'My son,' the father said, 'you are always with me, and everything I have is yours. But we had to celebrate and be glad, because this brother of yours was dead and is alive again; he was lost and is found.' – (Luke 15:31-32)

Now the Non-Prodigal Son, as you might imagine, was pretty browned off by all of this. While his Prodigal Brother was off having a good time, he stayed at home, having to deal with his crazy Dad, and trying to improve the fortunes of the family farm with only half of the assets left. And amazingly enough, he managed to do well, through hard work and made the farm successful.

So his no-good Brother comes home, and what does Dad do? Well, he slaughters the fattened calf (the one the Non-Prodigal Son was hoping to take to market next week and sell, so they could buy much needed improvements for the farm).

Worse yet, at the homecoming party, the Prodigal Brother starts hitting on the Non-Prodigal Son's girlfriend. Before long, the two of them are living in the basement. The Prodigal son sleeps until noon, refuses to help out with any of the chores, and worse yet, refers to the Non-Prodigal son as "Bro".

Of course, the Non-Prodigal son complains to Dad about all this, but Dad will have none of it. "He hath returned!" the Father says, with a wild look in his eye, "He Hath Returned!".

"What the Fuck does that mean?" the Non-Prodigal Son replies, "That makes no sense at all. He wasted half the money in the family and now you treat him like some sort of returning hero."

But Dad just repeats, with that far-away look in his eye, "He hath returned!"

The next day, around Noon, the Prodigal Son arises from the basement and says, "Hey, check it out, Bro, I got a new Tattoo!" and he rolls up his arm to reveal the phrase "He Hath Returned" inked into his bicep. "Bitchin' ain't it?"

"Ain't he something?" the Non-Prodigal Son's ex-girlfriend chimes in, wearing nothing but a t-shirt.

"That's it!" the Non-Prodigal Son shouts, "I'm out of here! I'm tired of Dad playing favorites. I'm not going to work my ass off for this family, only to have my efforts squandered by my deadbeat Brother and my insane Father!"

So he demands his share of the inheritance, which now, of course, thanks to his hard work, is nearly equal to what his Brother received, and leaves.

At first, he tries to follow the example his Brother lead, leading a riotous life and indulging himself with wine, women, and song. But he finds it all very shallow and unappealing. He realizes that his Brother must have been an idiot to find gambling, drinking, and prostitutes attractive in any way whatsoever.

So he returns home to the Family farm. The place is in a shambles. His Prodigal Brother has done nothing to keep the place up, and the fields lie fallow, choked with weeds. One skinny cow is all that is left of the livestock herd.

"I have returned, Father!" the Non-Prodigal Son cries out.

"Big Deal" His Dad replies, "Very Original. Where have I heard that before?"

"Well, aren't you going to welcome me with open arms and slaughter the fatted calf?" he asks.

"We can barely feed ourselves here anymore, thanks to YOU leaving. Do you think we can afford another deadbeat mouth to feed around here? And do you see any fatted calves lying around?" Dad replies.

His Brother, walking up from the basement, says, "Yo, Bro, whas up?" and tries to give him a high five.

The Non-Prodigal Son finally realizes that he was getting the shaft all along. For some reasons unknown, his Father would always favor the Prodigal Son, would always cover for him, make excuses for his failures, and try to protect him. And the Non-Prodigal Son realized that no matter how hard he worked, his Father would never appreciate him as much as he did his deadbeat Prodigal Brother. The whole game was rigged from the get-go.

So, taking his last few remaining shekels, he travels to Jerusalem and gets a job with a local business. Since he is used to hard work, within a few years he has put enough money aside to start his own business. And within a few years he is very successful and wealthy.

One day, on his way to work, he thinks about his Prodigal Brother and his Dad, and wonders how they ever made out. He thinks about sending them a post card or something, just to drop them a line.

But then he thought better of it.

The End.

Thursday, April 15, 2010

Time is money?

Time is the ultimate luxury item. Don't squander it.

Many folks complain they don't have enough time in the day to get things done. The complain that they want to do more in life, but can't seem to find the time. Businessmen say "time is money" and micro-manage their lives to make the best use of it.

Are all of these people actually squandering time? I think so. And recently I had a revelation.

Yesterday, I played 9 holes of golf and took a three-mile walk on the beach. No, it wasn't the weekend. And no, it wasn't a "vacation" either. I live in two places that are both vacation destinations, and it is easy for me to forget that what I do on a daily basis is what other consider a once-a-year opportunity or luxury.

How is it that I structured my life to make use of my time this way? Was I lucky? Or was it by plan? I would like to think the latter.

When I was younger, I was a very lazy person. To me, doing nothing was the best thing to do. I enjoyed school classes, but studying, doing projects and reports and all that drudgery, was an anathema to me. The best time of year for me was when school was out, and I could enjoy a lot of unstructured time. So perhaps this underlying desire was what motivated me to live the way I do.

During my working years, rather than follow the well-worn path others were taking, I struck out on my own. I lived on less and worked hard, invested my money and did well. At the right time, I was able to sell it all and move out of the big city and live the way I wanted to.

My friends all followed the well-worn path, buying larger homes, leasing fancier cars, and working harder and harder to get that coveted corner office and promotion. And of course, those goals never turned out to be as lucrative as they thought they would be - nor as profitable. It was a carefully set trap, it turns out.

You see, you only have a finite amount of time on this planet. You can make an unlimited amount of money, if you want, but it takes up a lot of your time, and thus subtracts from your time account. And yet many people chase the money, as if it were a scarce commodity, and time was infinite. It is, on the contrary, the other way around.

Consider your typical suburban couple. The complain they have no time in the day to get everything done. So they don't balance their checkbook regularly. They eat out in restaurants to "save time" (it takes longer to drive to a restaurant, order the food, and eat it, than it does to make a simple meal at home). Or they send out for pizza to "save time".

Of course, since they are not watching their finances and spending money on convenience items (to save time, of course!) they have to keep working harder and harder to make more money - so that they can afford all these "time-savers"! It becomes a circular logic, and a rat race. Or perhaps more like a rat on one of those wheels, running in place and never getting anywhere.

Meanwhile, time slips away, imperceptibly, year after year, until one day they wake up and wonder where their lives went. And it happens to most of the middle-class population in this country, year after year.

And where does the time really go? Television takes a lion's share - an average of 4.6 hours a day. Doesn't sound like much, does it? But subtract your sleeping, eating, commuting, and working hours from 24, and you'll see that television is taking nearly every other waking hour away from you.

Just as saving only "small" amounts of money can result in huge increases in your disposable income, saving "small" amounts of free time increases your available free time considerably. If you give up television entirely, you'll find you double or triple the amount of free time you have.

And once you stop paying for "time-saving" conveniences and do things yourself, you won't have to work so hard (which takes time) to pay for those time-savers. It has a snowball effect.

So what can you do to take your life back? To get back the TIME you have been squandering? It is not easy, and it takes courage, wisdom, and foresight. Not many can do it. Most humans, I am afraid, are doomed to lives of "quiet desperation," living as cogs in a machine, until they wear out and are replaced.

But a few of us - the lucky ones - can escape. While it isn't easy, it is totally worthwhile. But it requires that you re-think your whole life and your value systems.
1. Give up Television: Chuck it. Sell the damn thing. Cut the cable. TeeVee is a time waster and also designed to get you all riled up over nothing. The time saved is important, but moreover, the social cues it provides are horrible. Once you dump TeeVee, you'll stop acting like a lemming.

2. Get Control of Your Finances: Knowing where the money goes and why is key. You need to balance your bank and credit card accounts almost daily. You need to know, to the penny, what your net worth is. You need to know, to the penny, what your debt load is, and what your plan is to pay it off (amazingly, most people have no idea of their debt load, and have only vague plans on how to pay it off). Once you know where the money is going, you may be startled to see what you are spending on.

3. Re-Evaluate your Priorities: You may find that much of the money you spend every month is squandered on convenience items and also status items. And again, small amounts of disposable income are important. While it may seem that spending $10 a day on Starbucks coffee is cheap, in reality, even for someone making $100,000 a year, it is a big chunk of the disposable income. Many suburbanites are working like dogs so they can afford fancy cars and fancy houses. They pay a lot for a house in a suburban area, because it is near work. But if you had to live anywhere, would you be paying $750,000 to live where you are now? Ask yourself why you jumped on this treadmill.

4. Formulate a Realistic Escape Plan: If you are not happy with the modern middle-class suburban lifestyle, formulate an escape plan. It isn't easy, but I've seen it done, by many friends of mine. But you have to be realistic. You can't just up and quit your job and assume you'll find work elsewhere. And if you plan on going back to a simpler existence, you have to scale back your spending habits in advance. There are jobs in other parts of the country that pay less. Or you could start and run your own business. Or perhaps you can reorganize your existing finances so you can retire at age 50 - or even 40, if you are young enough and plan well in advance.
It is possible to live a different kind of lifestyle than what your neighbors and friends are all doing. It is possible to take back time in your life and make better use of it. But it takes a lot of courage to buck the norms of society, and not many are equipped to do this. Let's face it, most of us go through life trying to ape the behaviors of others, hoping that no one will notice that we are faking it and we don't really know what we are doing. And the joke is, that's what all of us are doing. Everybody else thinks you've got it together, while you look to them as a role model. Life is quite a farce, it seems.

Tuesday, April 13, 2010

Should you Unplug from the Grid?


Paying for services when you are not using them is a waste of money.

No, I am not talking about going back to nature and using a "hippie shitter" to recycle your own human waste. Nor am I talking about the crackpots who spend thousands of dollars on solar panels, wind generators, and car batteries, so that can save a few hundred bucks on utility bills. What I mean is that you can save hundreds of dollars a year disconnecting utility services when they are not in use.

Again, this blog is about how to live better on less money, not how to live like a pauper.   We have a vacation home on a lake in New York, and we do this on a budget. It does not take a lot of money to live large, if you are careful with your spending. Most people spend recklessly and end up living impoverished lives. Which is better, having a vacation home or leasing a new Lexus every 3 years? It is a lifestyle choice. I'll take the former. One way to do this economically is to pull the plug on utilities when you are not around. Sad to say, I was slow to pick up on this.

Here are some tips:
1. Seasonal Disconnects: In Florida, the cable companies offer a "seasonal disconnect" to snowbirds. Instead of disconnecting the cable every time you move North for the summer, they offer you a seasonal disconnect for a nominal fee per month. When you move back, you call them (or the service is automatically reconnected at a certain date). In most cases, they do not actually disconnect service, but rather just charge you less. They offer this, as having 100,000 people connect and disconnect service twice a year is just staggeringly expensive for them.

2. Power Disconnect: We have a camp at the lake which has power. Even if the circuit breakers are turned off for the winter, the power company (NYSEG) charges us $15 a month for service. I found out recently that we can disconnect service in the Fall and reconnect in the Spring, with no service charges. This saves $90 a year or more. If we did the same thing for our barn (which has separate service) we'd save another $90 a year, for a total of $180 a year. In the five years we've been there, this comes to nearly $1000 in savings we've missed out on. Bummer.

3. Winterize: Many people do not winterize their homes and instead rely on keeping the heat on over the winter (set at 50 degrees) to keep the pipes from freezing. The problem with this approach is that if the heat goes off (power failure, mechanical failure) the pipes will freeze, with catastrophic results. In addition, you will end up spending hundreds of dollars a month to heat an unoccupied house. So the savings in winterizing and "going cold" can be over $1000 a year, or a big dent toward your property tax bill.

4. Internet Service: This varies by provider. Some, such as telco DSL services, require you to disconnect service and then pay a reconnect fee, at whatever prevailing rates are offered when you reconnect. This can be a big hassle, as it requires you to reconfigure your modem and start over (which usually requires a call to India and an hour on hold). But others, such as Hughsnet satellite, will disconnect for six months and then automatically reconnect at a certain date, with no fee or charges. It is worth exploring either way.

5. Telephone Service: Our local telco offers to put telephone service on a vacation mode, for a nominal fee every month ($5). This way, you keep the same phone number, and don't have to hassle with a complete disconnect, reconnect and new phone number every time. But often such vacation disconnect will trigger a disconnect on your DSL service as well. So you have to be careful. I did this vacation mode one year and they never started billing me for the full rate for nearly two years. Under the law, they could only recapture three months back billing, which of course, was too bad for them.

6. Going All Cellular: Of course, cell service is one alternative to having a land line at all. For the cost of two land lines at each home, you can pay for your cell phone, which, chances are, you have anyway. I use a cell phone amplifier and a docking station to connect my cell phone to my house phones and have disconnected from the local telco. This allows me to have one phone number for both houses (and while traveling) and also use my house phones like a land-line, but in fact be making a cell call (and no more running around to find the cell phone when it rings, or having bad service). These are just a few ideas on how to handle owning a vacation home in an economical manner. You can save a lot of money on utilities (nearly half) by unplugging or putting on vacation mode while away. Live better by spending more wisely.

UPDATE 2021:  The greatest cost-savings was ditching the vacation home and spending our summers traveling by RV.   You can vacation, even on a cruise ship or at a resort, for less money than "owning" a vacation home.  It makes no sense to "own your vacation" and this is especially true for timeshares.

However, I did learn a lot from this experience.  Today we have only cell phones - no cable TV, no landline, no Internet connection.   This cut our communications expenses to less than one-quarter of what they were.  Not only that, it means we have robust Internet service (via cell phone hot spot) when traveling. 

Friday, April 9, 2010

What is Most Important to You?

What is most important to you?

It is a simple question, but one that few of us bother to ask ourselves. What are the most important things in our lives, and how are we going about preserving those things?

What are your priorities?

1. Your health and well-being?
2. A Spouse or loved one?
3. Your children or friends?
4. Owning a nice car or house?
5. Impressing people you don't know with your wealth and status?

The last two items on this list sound ridiculous when taken out of context. But for most people in America, items #4 and #5 are the top of their actual priority list, and really important things like #1-#3 are at the bottom.

Think I'm lying? Think about it. The divorce rate in this country is nearly 50%, and children are shuffled between parents like so many chattels. The vast majority of Americans are overweight, eat poorly, and rarely exercise, and have little or nothing saved for retirement.

And yet, we all have fancy cars and are mortgaged to the hilt to have houses we can't afford, right?

So re-read my question again and you'll see I was right. Today in America, we throw away spouses and children - trading them in like the leased cars we drive. We buy status goods to impress "others" - the unseen hoards of people who will allegedly be impressed by our ability to sign a loan document (but in truth, rarely are, as they, too, have signed similar loan documents and understand how little real talent it requires to own things).

It is a shame that in a country that harps about "values" we have so few real ones. And the people who harp about "values" the most seem to have the shallowest - whining about their "right" to inexpensive gas, or blaming the government for their self-induced financial woes.

In case you've really missed the point, what is really important to your own life, as we all will inevitably discover, is not owning things or impressing others, but first and foremost, our own good health and well-being, as well as the welfare and companionship of our spouse and loved ones.

To achieve these goals, you have to look after yourself. And by that, I don't mean going deeply into debt to purchase consumer goods that may make you feel good for a transient moment. Watch your diet, exercise regularly, and try to stay in good health. If you have no major health issues, you are very fortunate, so there is no excuse for allowing your health to degrade by overeating, smoking, and not exercising regularly.

And taking care of yourself and your loved ones means investing for your own future, not spending for the moment. Putting money in your 401(k), paying down debt, having money in your savings account. Yet so many spend all of their income and borrow yet more so they can have a new pickup truck and a deer stand, or a jet ski and a new car, while not funding their own savings or retirement. Once laid off, they cry "foul" as if someone else forced them to spend all their wealth and leave them destitute.

And by loved ones, I mean your real friends and loved ones, not abusive family members or baiting friends. I see many folks, often the same ones obsessed with impressing strangers, try hard to get into the good graces of the local cliques, whether they be in the neighborhood, at school, or at work. They desperately want acceptance from shallow people, who of course, will dangle it right out of reach. Or those who continually try to obtain acceptance from family members, who in turn respond with little more than abuse.

Find true friends and clutch them to your breast. Let the others go, for your own sake and your own sanity.

Take care of yourself, be kind to yourself. Figure out what is really most important to you.

Wednesday, April 7, 2010

High Deductible Health Insurance


If you are self-employed, you have to pay for your own health insurance.  The cost of health insurance can increase dramatically as you age.  Eventually, you will be forced to go to a high-deductible plan.  So why not cut to the chase and do it now?

Note:  See also my posting Understanding Health Insurance for more information on this topic.

I have a $10,000 deductible Blue Cross plan, which I am very happy with.  Presently, at age 50, it costs me $199 a month (Blue Cross called yesterday to wish me a happy birthday and raise my rates!). But when I started out at age 44, it was about $100 a month. Either way, it is a very cheap plan.

But wait, you say, $10,000 deductible? That's just crazy! Suppose you get sick?

Well, as I have noted before, you can get cradle-to-grave coverage if you want, but expect to pay about 5-10 times more than I am paying right now. If you want that initial $10,000 covered, it will cost you about, well, $10,000 additional a year. Pretty simple math, eh?

The advantage of having a high deductible plan is that for everyday medical needs, you may get some prescription coverage, and occasional office visits with a $40 co-pay. So for most healthy people, it covers your basic medical needs throughout the year at a pretty low rate.

If you need additional services, you do have to pay a la carte, but the real kicker is, you pay at Blue Cross' pre-negotiated rates, which are generally 30-50% less than what a cash customer pays. By the way, these sort of rates illustrate how elastic medical care pricing is, so never be afraid to ask for a discount if you are saddled with medical bills.

But what happens if you need more medical coverage than that? Well, my experience has been, as a fairly healthy person, that in a bad year, I may run up $2000 in medical expenses - an MRI, for example, or a Colonoscopy.

In situations like these, having a $2000 deductible versus a $10,000 deductible really makes no difference. Either way, I have to pay $2000 in medical expenses. But with the higher deductible plan, I save more than $2000 a year in premiums.

In short, it works out even, if not better. If I go a year without any major medical expenses, the savings in premiums more than covers any deductible payments in other years. Over a period of several years, you will save more in premiums than you will pay in out-of-pocket costs.

And as my 50th Birthday illustrates, as you get older, rates will steadily increase. Actually, they will dramatically increase, particularly when you reach that scary gap between age 60 and Medicare eligibility. During those awkward years, you can expect your insurance premiums to skyrocket, perhaps to over $1000 a month, even for a high deductible plan. For most people, going to high deductible is the only option at that point in time.

So the net result is this: Going to a $10,000 deductible is not something you will never do. It is something you will inevitably do as you get older. That is, unless you are made of money. But if that was the case, chances are you are not reading this blog.

So why not cut to the chase and get the deductible you are going to get at age 60 anyway? The savings in premiums over the years will help offset those staggering costs during those last "gap years" prior to Medicare coverage.

Take the savings in your health care premiums and put them in a savings account. Pretty soon, you'll have that $10,000 in savings, if you need it to make the deductible. Within a few years, you'll likely have tens of thousands of dollars saved.

It is unfortunate, but in the medical care debate, most Americans want all the coverage in the world, but they want "someone else" to pay for it. We demand cheap premiums, but insist that the insurance companies (the bad guys, always) pay for every darned little thing, even our band-aids.

But here's the deal: The insurance companies have to at least break even or make a profit. And the overhead of paperwork they have is staggering. If they pay out $5,000 a year in medical benefits to you, you have to expect them to collect, on average, about $6,000 to $7,000 a year at minimum in premiums, just to cover costs.

Having a higher deductible reduces those costs and thus keeps your premiums low. Insurance is reserved for when you truly would need it - when some catastrophic accident or illness occurs.

And a high deductible has the secondary effect of forcing you to consider cost in your treatment. Yes, you do have treatment options and costs, and can make informed decisions as a consumer. When someone else is picking up the tab, money is no object. As a result, the consumer cares less about the bills, and the practitioner feels emboldened to increase them.

In order to bring some sort of sanity to health care costs, we need to have some mechanism where someone in the chain cares about pricing.

There Ain't No Such Thing As A Free Lunch!