Friday, June 4, 2021

Got To Stick With It, Donnie!


After more than a decade and nearly 5,000 posts, I have learned a lot about blogging.  Sadly, most bloggers give up after a short period of time.

Donald J. Trump had a blog.  Imagine that.  After being shut out of Twitter and Facebook, he decided to try the blogverse.  It lasted 29 days.  I imagine his followers couldn't find it, as it wasn't on Facebook and easy to find.  No doubt they were challenged by the long format, too.

It is pathetic, but it appears that the Trump blog has fewer hits than even my little corner of the internet, scoring only thousands of hits, rather than millions, as he had back in his Twitter days.  So what went wrong with the Trump blog?  I mean, it was a wide-open platform for him, with no "censorship" or whatever.  Why didn't this format work for him?  I think a number of reasons:

1. Put a Fork It It:  He's done.  Former Presidents fade away, and while the GOP is pledging fealty to Trump, I think a lot of mainstream Republicans have moved on.  Like I said before, my Republican friends (and no, they don't have tails!) were pro-Trump up until January 6th, at which point, all their Trump yard signs came down at once.  There is only one person left on the island, that I am aware of, that still is a "believer" and even then, they have a discreet "Not My President!" sign in their living room window (left over from the Obama years) and I think even that is gone now.

2. The Media:  Trump had 22 million followers on Twitter, but 19 million of them were journalists. The other two million were sock-puppet accounts from Russia.  The media loves Twitter and thinks that a posting on Twitter is a news story.  Not many ordinary folks are on Twitter or follow it.  Who has the time?  With Facebook, Instant Messaging, E-mail, TikTok, plus all your porn and hookup sites you visit, who has time for Twitter?  I am being facetious, but I know folks who do look at their phones all day long, and they do have to triage what is and isn't important.  And Tweets fall off the map pretty quickly.  And let's face it, the latest Tweet outrage will be reported dutifully by the news - so why bother following Twitter?   Since January 6th, the media has stopped amplifying Trump's remarks, mostly because they no longer sell clicks anymore.  Supporter or detractor, you don't really care much about what Trump has to say, now that he is out of power.  On the other hand, a juicy story about Biden generates hits!

3.  Nothing to Say:  If you blog, you have to say something, otherwise why bother?  And Trump's litany of grievances, well-suited to snarky Tweets, don't play well in the long format.  A blog entry that is just Trump saying "Stop the Steal!" 500 times isn't very interesting.

4. Persistence:  Trump wanted to make a splash, but it can take years to develop a blog following, even a modest one.  But that isn't Trump's style, is it?  He's not the guy to slowly build anything up, over time, laying a foundation that will be the base for something long-term.  No, he's more of a hit-and-run kind of businessman.  Make a splash, make a little money, and then run away from the smoldering wreckage you leave behind.  Business deals, casinos, marriages, the Presidency - it is a pattern with him.

5.  Vanity:  Once it got out that Trump's blog numbers were lame, well, it was the writing on the wall. This is a man with the emotional balance of a 6-year-old - a spoiled brat six-year-old.  If he can't win at a game, he throws a tantrum.  I am sure when he was a kid, playing Monopoly, the threw the board in the air, once his brother put hotels on Boardwalk and Park Place.  Years later, he would do the same with the real Atlantic City.  Trump cannot stand to be embarrassed or humiliated, so he pulled the plug on the blog before he could get it started.

Blogging and Tweeting are wildly different things, as is Facebooking.  Putting things on your "Wall" on Facebook is akin to spraying graffiti on a real wall.  Ditto for Tweets. Messages are short and simple, and there isn't a lot of thought put into them.  Blogging, on the other hand, is a more contemplative pursuit.  Contemplative - does that sound like Donald J. "short attention-span" Trump? Hell no.

It is emblematic of his problem that towards the end he was putting up ten posts a day.  I am kind of doubting they are of any great length.  The master of the short-form was flummoxed by the long-form.  Trying to Tweet on a blog site is a square peg in a round hole.

The Internet has a short attention span just as Trump does.  I think people are ready to move on to the "Next Big Thing!" and Republicans are focused more on the 2022 midterm elections than they are on the 2024 Presidential one.  And it is possible they may find Trump more of a liability than an asset, with each passing day.

There are plenty of platforms that Trump can use to get his message out, including his own website and blog.   Tellingly, these don't seem to garner much interest these days.   Is it the man, the message, or the platform?   If your message doesn't resonate without the platform, that says something.

It says a lot, in fact.

UPDATE:  After writing this, I realized that the medium was essential to Trump's success, and this reminded me of the phrase coined by Marshall McLuhan, "The Medium is the Message" which I never really understood, perhaps, until now.  Trump without Twitter, or some Twitter-like platform, that allows him to bully and prod and provoke, just doesn't work, as his blog illustrated.  He wants to get a reaction out of people, and the media, who is hooked on Twitter, was all-too-happy to react.  A dusty old blog?  Entirely different head.

The medium is the message!  I think I get it, now.


Thursday, June 3, 2021

AT&T Personal Cloud? Uh, No.


The Cloud is touted as the answer to everything.  What was the question, again?

I recently got a new (used) Galaxy phone.  It was a used AT&T phone, whereas all my old phones were used T-Mobile phones.  Funny thing, I could stream data using the T-Mobile phones as hotspots without any problems, even though our AT&T "prepaid" plan didn't provide for hotspot service.  I am guessing that somehow the AT&T people couldn't detect hotspot usage (which was done using a T-Mobile app) on a T-Mobile rooted phone.  It was great while it lasted.

So I had to "upgrade" ten dollars a month and this AT&T "Personal Cloud" appears as an add-on to my service, which I think is free of charge but I am not sure.   The AT&T site is not really clear on this, until I clicked on "plan details" and read:

Personal Cloud: AT&T Personal Cloud 100GB is included with your plan. The Personal Cloud app provides a way to safely store and protect valuable mobile content in the cloud. Through the app, customers can backup, sync, restore, access, create, and share content. For more info go to att.com/prepaidcloud.

...which is good because the ordinary charge is $4.99 a month, which I didn't want to pay.  The app was loaded on my phone, and I guess it sort of works.  It keeps talking about backing up "messages" whatever that means.  Instant messages?  Who the hell wants those backed up?  I delete all IM's the moment they are sent to me - as well as call logs.  I don't need that crap clogging up my phone.  For that matter, I am ruthless about deleting e-mails.  My inbox never contains more than a few e-mails, which is sort of a "to do" list of either e-mails I have to respond to, things I ordered online I need to watch for, or something I need to attend to.  Everything else gets erased.

(Oddly enough, you can find most of your e-mails, the important ones, anyway, in your SENT box, so all is not lost if you delete an important e-mail.  Important e-mail is something of an oxymoron, though). 

Actually, not backing things up is always a good option.  When a hard drive crashes and you lose data, there is a brief period of mourning, followed by a period of exhilaration.  All that crap you've been carrying around - GONE!  It is like my friends who "lost it all" in a house fire.  They missed a few things that were of sentimental value, but realized that most of the stuff in their house was junk - and the insurance check bought them much nicer, newer things.  I can't wait to see Marie Kondo set her house on fire - the ultimate "tidying up!"

By the way, I am not recommending arson - it is illegal and the insurance company won't pay out.

When you get older, you realize that a lot of the stuff you drag around in life is a burden - like Dickens' Marley with his chains and lockboxes.  We have a trunk full of photos and photo albums which we have not looked at in well over five years, maybe ten.  They are probably all moldy and faded.  We have no children to leave "memories" to and that is probably just as well.

My mother was a shutter-bug and took thousands of photos and had them made into slides.  No one looked at them very often, and later in life, even she and Dad stopped looking at them.   When they died, someone in the family inherited them like a hot potato, but since slide projectors and screens are sort of obsolete, I doubt that anyone will look at them, ever.  Without Mother's drunken commentary identifying each slide and what its relevance was, it is hard to make sense of old photos.

This is why I say, if you want to go this route, put the photos in a photo album (physical or online) and put a caption and description with each one. Otherwise, like my Grandmother's photo albums, the photos become meaningless.  You might as well be looking at random tintypes in an antique shop - where so many end up, unidentified and forgotten.  And if you post the photos in an online album, back them up somewhere, lest you end up a victim of an outfit like Webshots, who decides to "move in a new direction" and then deletes all your photos and captions.   The Internet is not permanent - it just seems that way.  And no, the "Wayback Machine" (Internet Archive) doesn't archive everything but mere snapshots (if you'll pardon the pun) of portions of the net, from time to time.

But I digress.  Or did I?  What I have learned late in life is that it is OK to "let go" of papers and records and photos and whatnot.  It is only young people who feel the need to save everything and reminisce over old photos and whatnot.   I think it is some way of denying death  - or perhaps finding meaning in life.

When you've cleaned out a few relatives' houses and even those of non-relatives, and realized that an entire lifetime of photos, mementos,and records all goes to the dumpster, you realize how foolish it is to try to "save" things.

For example, Mark's Dad saved tax records and bank account information for 20 years or more.  The IRS audits only back seven years, so if your records go back that far, you are pretty well set.  Why he kept cancelled checks from 1985 is beyond me.  We made a bonfire and lit everything up, lest someone paw through the trash and harvest an account number or something.

A neighbor down the street died and his house was abandoned for many years.  They tried to rent it out, but the Pacific Electric circuit breaker box caught fire.  The fellow was a commercial artist and his heirs didn't want anything in the house.  We inherited a lot of his art - the arts association has even more of it.  But there were boxes and boxes of files and "stuff" that ended up on the dumpster.  I read some of it - a letter dunning a restaurant chain for work he did designing their logo.  Interesting, but pointless - to even him.

So this urge to back up and save things is sort of pointless.  They couch it in terms of how you can "recover" your data if your phone is lost or stolen.  All your contacts!  You want to keep that, right?  Well, like my t-shirt collection, it pays to go through things every so often and ditch the ones that no longer fit.  I lost "all my contacts!" when my phone died and frankly, it was a blessing.  So many of them were for former clients I had not contacted in over a decade or things of that nature.  Did I really need that data?  It takes seconds to click on "add contact" when someone e-mails or calls or texts, so the really important people are "restored" within a matter of days or weeks.  As for the others?  Well, if I really needed to call them, I would find their number.  If not, why bother?

So, I have this free cloud, but probably don't need it.   Sure, since it is free, I may use it, to back up my music (11,000 songs), Books (thousands as well), and photos (geez!).   Problem is, to back things up, you need to use Wifi (for the phone), and the volume of data is pretty huge at least to get started. So the first time you log onto Wifi, well, it slows your phone down a bit.  For the computer, I am using the phone as a hot spot, and backing up all my files from the computer will pretty quickly eat up my data plan.  I suppose once the files are uploaded, the incremental uploads won't take too long to do.

The "app" for the phone seems to sort of work, but I get weird messages - that it "found new pictures" but when I click on it, it gives an error message.  When I go to the website, it is easier to see what is backed up and download and upload data.  But I also realize that it didn't back up diddly from my phone, or at least not all the data, from what I can see.  If you read the reviews online about the app, there are a lot of one-star reviews - people who don't want to pay $4.99 a month and can't figure out how to make AT&T stop billing them (Hint: switch to Verizon!). Others point out that the instructions on how to use the service are a little opaque, to say the least.

But all that being said, is it worth it? Because in the long run, nothing on the Internet is forever.  These files will only exist on their server so long as I am an AT&T customer and have this plan.  If I downsize to another plan, the data goes away after 30 days, unless I pay $4.99 a month as an "add-on" to the plan.  In addition, there is always the possibility of a server crash and data being lost, spindled, or mutilated.  And we all hate when that happens.  But if you read the ToS, basically AT&T promises to use "best efforts" to preserve data, and if valuable data is lost, they are not on the hook.  I mean, they are not fools - the liability would be enormous.

I guess since it was "free" I will play with this cloud thingy, but so far, it seems to be of limited value and of limited time. It is not some vault you can keep data in forever, but more like a backup hard drive that exists so long as you keep paying for it.

Or until they change their mind about it.

Wednesday, June 2, 2021

People Much Smarter Than Me...

There are lots of people in this world a lot smarter than me.  But what they have to say is important based on what they are saying, not because they are smart.

A reader sends me links to two interesting articles about Bitcoin.  The first is about the security of Bitcoin and how it is somewhat laughable - after all, so many exchanges have been hacked, and so many Bitcoins have been lost or stolen.  And when that happens, you have no recourse, as no one runs the damn thing.  If you have a $100 bill and you put it through a shredder, you can mail the pieces to the Treasury Department and they will send you a new $100 bill.  There are people in the loop, and mistakes and errors can be corrected.

Contrast this to the guy in England who threw away his hard drive, thinking his Bitcoins stored on it were worth only pennies.  Today, they are worth millions.  He is trying to bribe the local council to let him dig through the landfill to find the hard drive.  It is sad to read about.  It reminds me of the guy who lost a winning million-dollar lottery ticket and was so despondent he killed himself.  The Bitcoin is the ultimate bearer bond, it seems. You lose that piece of paper (or stored encryption) and all is lost, irrevocably and for good.

But the weird thing about Bitcoin and other "blockchain" cryptos is that the "ledger" contains a list of all transactions for all "coins" for all time.  Imagine the dollar bill in your hand has a list of every transaction it has been used for, as well as a list of the trillions of transactions of every dollar in the United States since December 23, 1913.   As you can imagine, this document would get rather large in a hurry.  What's worse, people are vandalizing the ledger by inserting garbage text, prayers, photos, pornography, classified government documents, etc.  It isn't hard to see why each new "coin" takes longer and longer to "mine" and why each transaction takes longer and costs more.  And the ledger can never, ever, be edited.

The second article concerns trust, and this is an interesting take on Bitcoin.  People claim Bitcoin is more trustworthy, or more precisely does not rely on trust.   And as a person with trust issues, this is appealing, until you realize that a computer has no trust at all, other than to do as it is programmed to do.  And if the GPS says drive off a cliff, well, it will drive off a cliff.

The Bitcoin whitepaper was published in 2008. What else happened in 2008?  Obama was elected president. Wait, no, that's not it. Oh yeah, the Great Recession.  That.

People lost a lot of money and a lot of trust in financial institutions. Of course, the cause of the Great Recession wasn't malfeasance on the part of any one financial institution rather a lot of greed on the part of a lot of people. And our system proved itself to work. Sure, people who over-mortgaged their mini- mansions lost money, but they were the ones that were victims of their own greed.

And yes, a lot of people lost money in the Madoff Scandal. Then again, our human-based legal system allowed a lot of those profits to be clawed back from people who cashed out early. Nobody was made whole, but at least some of the money was returned.  In fact, a vast majority of the money will be returned to investors.

Contrast this with Bitcoin and the Mount Gox fiasco - among others – where no money was returned to anybody.  You lose a Bitcoin, it is lost for good.  And Bitcoin "exchanges" rely on human trust and reputation to operate - and are just as weak as any other man-in-the-loop institution out there.

As we learned in Commercial Paper, a check deposit can be backed out of your account up to a year after you've made it. Our financial system has a man-in-the-loop for a reason. Mistakes can be reversed and corrected for the most part. And if not, Banks often take it on the chin in order to maintain their reputation.

For example credit cards. If your credit card is stolen, and you report it, you're not liable for any charges, even if the bank accidentally pays them. The banks lose a lot of money this way, but it instills confidence in the credit card system. There is no such backstop if your Bitcoins are stolen.  There is no recourse, no way to reverse transactions, and in fact, no one to call if you have difficulty.  Not even "Mike" in Bangalore to tell you to turn your computer off and on again.  Tell me the customer service number for Bitcoin and maybe I'll change my mind about it.  Granted, customer service at Bank of America can leave a lot to be desired - but at least it exists (and actually it isn't all that bad, if they are not too busy and you get the right person on the phone).

There was a case recently where a man in Australia mistakenly received a deposit into his bank account of a million dollars or so. Rather than alert the bank, he tried to go and spend the money.  When the bank realized the error, they reversed the deposit from his account, but of course much of the money was missing.  If this was a Bitcoin account, yeah he could have gone out and spent that money. But it under normal banking laws, someone accidentally deposits money in your account, it doesn't belong to you. And if you spend it, that's stealing. And yes, he was facing criminal charges.

So I agree with Mr. Schneier, this idea of "In Crypto We Trust" is flawed. You can't trust a machine to do the right thing all the time, only what it's programmed to do.

What is refreshing about Mr. Schneier's articles is that he analyzes things and presents facts and analysis.  You may disagree with him, and can challenge the facts and the conclusions - but there is a "there" there to analyze. Contrast this to the "Crypto Experts" on the Internet who say oddball things like, "My target price for Bitcoin is $100,000 before the end of the year!"  Why?  What facts are used to base this projection?  There aren't any,  nor any reasoning, either.  This is not to say the Crypto-fools won't bid Bitcoin back up into the stratosphere yet again (and it crashes yet again) only that there is no logical reasoning behind such projections - or at least nothing that can be analyzed.

Mr. Schneier is smarter than I am and clearly knows more about this sort of thing, and I respect his opinion, not because he is smarter, but because he lays out his arguments logically and doesn't just make conclusory statements.

That being said, you can analyze this from another angle, without even having to know anything about the technology or its inner workings.  From a market standpoint, you can look at this from how it is presented (Hype, FOMO, and the usual carnival barker techniques), and also from basic market logic.

As I noted in my previous posting, Bitcoin is an "investment" in the concept of scarcity itself.  There is nothing underlying Bitcoin, nothing physical - just the idea that people want to buy it.  If more people want to buy than sell, the price goes up.  If more want to sell than buy, the price goes down.  The recent ups and downs in Crypto have little to do with Elon Musk's tweets and more to do with how they affect the supply and demand balance.   You don't need a degree in computer science to understand this, just common sense.

If enough people decide there is no "there" there in Crypto, the whole thing could collapse overnight.  When you buy Bitcoin or any crypto, you are investing in the idea that "some greater fool" will pay more than you did.  Since the Great Fool Shortage of 2008, things have turned around for those who want to exploit fools. In fact, the same fools who thought they would make millions buying-and-flipping houses are often the ones buying Bitcoin or the latest IPO, convinced, "This time for sure!" it will pay off - like Bullwinkle with his magic hat, or Charlie Brown trying to kick the football.  The Lucy van Pelts of the world are very persuasive, aren't they?

So, I leave it to the Schneier's of the world to dissect Crypto and relate why it has its technical faults.  I can only look at the obvious stuff that should be apparent to anyone who thinks about it for a while.  For example, I can "take down" this piece of low-hanging fruit that was in the comments section of Mr. Schneier's website:

tobi • February 12, 2019 7:53 AM

Cryptocurrencies are not useless. They are functional money. You can pay with them.

They give a bank account to billions of unbanked people.
They provide an exit from defunct currency systems such as in Venezuela.
They make international payments far cheaper and quicker.
They are a way for companies to save credit card fees which are 1-3%.
They make micropayments possible which the existing financial system seems unable to provide.
They are programmatic money enabling lots of new use cases and innovations. Any teenager can now receive and send money programmatically. No licenses.
All of the above statements are patently false and easily provable as such. They are not functional money, and no, you cannot pay with them.  I am not sure where "tobi" is coming from, other than to cheerlead for a currency that has never had any currency.  Taking his items one at a time:


Bank accounts?  Sure, you can set up a "wallet" with an "exchange" but to fund it, you have to link it to a bank account with money in it.  Yes, there are a few "Crypto" ATMs out there, but they are few and far between.  Even if you could "fund" your exchange account with your unbanked cash, since you can't spend it anywhere (see below) it isn't really a functional bank account of any sort.


As an "Exit" for a "defunct currency" I suppose he has a point - provided that the country in question doesn't outlaw the exchanges, as China is poised  to do (or is doing) to prevent such a capital flight.  But this illustrates that the only real uses of Bitcoin and other crypto are to skirt the law.


International Payments cheaper and quicker?  Maybe when the system was new, but today, it can take hours to "decrypt" a transaction in a mining machine(s) and the electricity required is staggering - and hence the costs involved.  Exchanges don't operate as charities, and charge fees for sending and withdrawing money.  A traditional wire transfer is now faster and cheaper than Bitcoin.  In fact, my European friends tell me they can do this from their phones, in a matter of minutes.


Save on credit card fees?  Not bloody likely on two counts.  First, the cost of Bitcoin transactions can far exceed that of credit card fees - in the tens if not close to a hundred dollars.  The fantasy of swiping your phone and paying for your Starbucks with Bitcoin will forever remain a fantasy - and it doesn't look like any of the other "coins" have cracked this problem either.   Second, no one takes it as payment, other than drug dealers, arms dealers, human traffickers, and as we learned lately, computer hackers.  And unlike credit cards, there is no recourse if your "coin" is lost or stolen.  I've had credit (and debit) cards "hacked" more than once.  I never lost a penny in those transactions.

Micropayments?  Again, make me laugh.  I am going to wait a half-hour or more and pay ten or twenty bucks so I can pay someone ten dollars?  It just isn't feasible.

Programmic Money?  I am not even sure what that is, but a "teenager" buying Bitcoin is problematic, as when he reaches age 18, he can renounce any contract he signed (including the one he signed with the exchange) which is why no one lends money to or contracts with, minors.

The funny thing is, and no one seems to want to ask this question, is that Bitcoin has had over a decade now to show it can work as a currency - so proponents (including the Sooze) have pivoted to calling it "virtual gold."  How long before the plebes see through that one?  For at least the last five years, it has been more expensive to process a bitcoin transaction than to use a credit card, at least for very small, everyday transactions.  As this site explains, the cost varies and is unpredictable, as it depends on the volume of transactions on the network (!!).  So you make a purchase with bitcoin and the cost is... unknown.  Sounds swell.

Businesses like predictability as they can plan around it.  Republicans have been pushing this false narrative that businesses hate regulations and want them all abolished, as they are "holding back" America from being an economic powerhouse (which it already is).  The plebes, who never ran a business, bite on this nonsense (and Bitcoin, too!).  But the reality is, Businesses would prefer fewer regulations to comply with, but what they really want is consistent regulations that don't change from day to day, month to month, or year to year.

California decides that any product with a "cancer-causing chemical" has to be labeled, and businesses balk at the burden.  Then they realize that all they have to do is label every product they sell as containing cancer-causing chemicals in the State of California (but apparently cause cancer nowhere else) and they are  in the clear.  A small change to the owners manual, or, as was the case with a piece of knock-down furniture I bought a few years back, a slip of paper stuffed in the packing box, with the requisite warning - that's all you need do.  Done.  Finished.  Move on.  Leave it be.

Predictability is what business wants, which is why the car companies fought Trump on loosening emissions and mileage regulations - they had already budgeted for this, in production plans that go ten years out.  Ford doesn't want to throw away all the R&D that went into their new hybrid pickup truck (a neighbor has one - makes my King Ranch look like a model T!) or their new electric pickup.  GM doesn't want to throw away all the carbon credits they bought from... Elon Musk.  Steady as she goes, is what they crave.

So it seems unlikely to me that "business" would want to jump on the Crypto bandwagon, other than to do a splashy press release (as Kodak did) hoping it might spike the stock price.  It is like all the hoopla around "AI" and how everyone is falling all over themselves to be "diverse" these days - in a year, much of it will be forgotten.

A "currency" that drops by more than 50% in value in a matter of hours or days isn't feasible or predictable for business - or even for the individual.  Even in the worst days of the recession of 2008, I didn't lose but maybe 1/3 of the value of my portfolio, over a period of months.  And even then, by the end of the year, it had recovered all of the losses. Compare the volatility of anything - any other currency, commodity, real estate, stock, or whatever, and Crypto comes up lacking - shooting up and down in value in response to millions of minions responding to tweets of celebrity influencers.

This is the future of "investing"?

I think not.

Tuesday, June 1, 2021

The Labor Shortage

Well, we sent all those Mexicans packing. How's that working out?

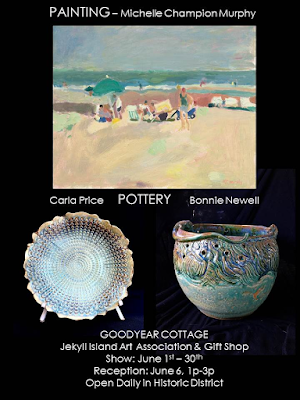
Today was an odd day.  We spent the afternoon in the golf cart, driving around to various restaurants, bars, hotels, and gift shops, putting up posters for the Arts Association.  Every month there is a new show in the gallery, and in addition to advertising in the paper, on Facebook, and wherever else, we put up these posters all around the island.  The local merchants are very cooperative in this regard.

This Sunday, there is a reception for the artists.  Small snacks and wine is provided, free of charge.  I am to bar-tend.  Here is my wine list. Don't miss it!

Wine List

 Sparkling:

          Cava: Juame Serra Cristalino

          (Catalonia)

Red:

          Cabernet Sauvignon:

          Woodbridge (California)

           Cabernet Sauvignon/Merlot:

          Frontera Concha y Toro (Chile)


White:

          Chardonnay: Woodbridge

          (California)

          Pinot Grigio: Member's Mark

          (California)

           Savigon Blanc: Oyster Bay

          (California)

Rose:

          La Vielle Ferme (France)

 Beer:

          Stella Artois (Belgium)

As you can see, we sort of punished the Pinot Grigio people.  We have a  budget, so none of the wines are very expensive.  Hey, it's free!  Don't complain!

Anyway, putting up the posters was a lot of fun, driving around the island in the golf cart and seeing the sights and whatnot.  The new hotel is almost complete, and they are putting the finishing touches on the new condos at the marina.  A good excuse to get out.

Mark spent the morning help "hang" the show - although mostly he was there for the "3-D" artists, setting up the pottery on pedestals and plinths.   So he was ready for lunch, and we thought we would eat out at a restaurant, which is not typical for us.  Someone recommended the oyster po'boy sandwiches at the Jekyll Market, but when we got there the place was mobbed.  The whole island is packed - on a Tuesday!  We have been gentrified and people are "discovering" our little abandoned island.  No doubt, my videos were to blame.

So we were disappointed, as Mark didn't want to wait.  Too bad, too, as I am sure they were good.  You can't help but like a grocery store that has a bar in it, serving draft beer.   Makes those $8 jars of pickles seem more attractive.

So, where next? Well, Rob's Place - the Sunrise Grill!  Best fried shrimp in Georgia and the beer is ice cold and..... they are closed!  This is not usual, but after a slammed weekend, the staff needed time off.  We've been a fan of Rob since he was bartender at the Hampton Inn, making the best fried shrimp and other appetizers in a kitchen the size of a closet.   But maybe next time.  Everyone needs a day off.

Hey, there's this new restaurant that opened up where the ill-fated Jekyll Seafood Company was located - "Sweet Georgia's Juke Joint."  Maybe they have some hot wings and cold beer.   The menu was very limited and kind of pricey, but what the heck.  Well, we get in there and in front of each chair is a plastic puck epoxied to the table or bar, saying you have to download an "app" by taking a picture of this barcode, in order to order your food.  So in order to do this, I need to download an app that allows me to scan these codes to download the app.  Then I have to download the app, then order my food.  The bartender (we are sitting at the bar) offers to help me download the app on my phone, rather than just pouring me two beers and ordering a dozen wings.  So we noped out of that.

OK, what the heck is going on?  A quick review of the Google reviews tells the tale - they can't get help, so instead of having waiters, they have an "app" which is fine for McDonalds, but not for a sit-down restaurant.  Big signs up front announce that they do NOT take cash, either (not that it matters to me).  For a fast-food place, maybe I could see this - downloading an "app" for Mickey-D's might make sense.  For a one-time purchase of food at a restaurant that has two locations (one in Atlanta)?  Nah.

We are starting to see a pattern here.  The Jekyll Market is overwhelmed with customers and not enough staff in the kitchen.  Rob has to close because his staff is exhausted.  A restaurant resorts to apps to replace waitresses.   This is weird.

So where to go?  Well, Rob took over the Golf Course restaurant and the tourists don't know about it.  So off we go.  We get there and it is not crowded.  Two beers and oyster Po'boys and boy they come out scalding hot and melt-in-you-mouth.  Rob knows how to run a restaurant!  So our crises is averted, for the time being.

We got back in the golf cart and drove around to put up the posters, including at a local hotel where a friend of ours is a manager.  She pulled in behind us and gave us a big hug and looked very sad. "What's the matter?" we asked.  "I've been working 12-hour shifts for a week now, without a break!" she said.  And of course, as a salaried manager, no overtime.   I felt bad for her, but it was the same old story - no one will work!

On to the Villas by the Sea - home of the very reasonably-priced Driftwood Bistro restaurant serving "down home" Georgia cuisine.  There is a line out the door - two-hour wait for a table!  The reason stated by the staff for the delay is lack of help.  We tell a hapless foursome about Rob's new place at the golf course.  Hope that helped.

On the way back, we stop at Tortuga Jack's to put up another poster.  Same deal - they are slammed and not enough help to handle the crowds.

It is almost like God is trying to beat us over the head with this.  Businesses are short of staff and help.  Help wanted signs are everywhere.  The local Dollar Tree has bare shelves and a stockroom overflowing with inventory because no one will work stocking the shelves.   This is just getting out of hand.

Why is this happening?  I think there are several causes, some short-term, some long-term.  The problem will not go away quickly:

1.  Unemployment:  We keep extending unemployment benefits, just as we did during the recession of 2008, when "Help Wanted" signs proliferated as well.  What's worse, with bonuses provided to unemployed workers, many were making more money on unemployment than when working.  In addition, many States suspended the requirement that you be "looking for work" so people could just sit at home and do nothing and collect a check.  It is Andrew Yang's socialist fantasy brought to life with horrific results - restaurants turning to automation to replace missing workers!

2. Immigration:  Trump's stupid wall kept no one out, but his aggressive immigration policies sent a lot of people back.  Maybe the person waiting on you at the table wasn't from Latin America, but the busboy or the dishwasher might have been.  With those jobs vacant (and no American willing to take them) restaurants are struggling.  And let me tell, you, having worked as a dishwasher, it is a messy, disgusting job!

3. Aging Population:  So many baby boomers are retiring and the next generation isn't quite as large. As I noted early on in this blog, the age pyramid looks more like a minaret these days.  It is not that the next generation is smaller only that it isn't large enough.   There are too many people not working and not enough people to work to support them.

So what does this mean?  Well, Katie-Bell, it ain't quite the end of the world.

First of all, the extended unemployment benefits will end, eventually, just as they did in 2009, and people will go back to work.  More liberal immigration policies will mean more foreign labor to fill some of these jobs that Americans simply won't take.  And many older people - many who did not save for retirement - will go back to work to make an extra buck.

Some of these places are paying $15 an hour - that's thirty grand a year!  At one local store, they had a sign up saying, "Now Hiring!  Interview NOW, Go to work NOW!"  In other words, none of this, "We'll get back to you!" nonsense, but rather they put the Wal-mart smock on you and put you to work stocking shelves, right away.

Thirty grand?  Might not seem like a lot to you high-flyers who have "careers" but it is what I live on, quite comfortably, right now.   I might consider something like that, part-time at least, to supplement my income, or more precisely, reduce the need to tap into my 401(k) for another year.  It is nice also to have something to do.  I mean, volunteering to put up posters is fun and all, but it is much more fun to get paid to do something.

So I suspect many an oldster will look at these "Help Wanted" signs and say, "Why Not?" just as a friend of mine, who has a generous pension, went to work at a number of places, as he "likes to keep busy" - and that is an admirable trait.

Over the long run, the situation will sort itself out.  Nature abhors a vacuum.  But part of the problem, as I see it, is that to attract more people into the labor force, wages will (and are) going up.  People have been whining about a $15 minimum wage for many years.  Funny thing - it has pretty much arrived, not due to legislation, but because employers are desperate for workers.

But higher wages means higher prices.  Lunch was $60 and I can't afford that very often - it buys an awful lot of groceries!  So with higher prices (inflation) a lot of older people who stopped working may decide to go back to work, as they may perceive (rightly) that you can't be too thin, too young, or have too much money.  For those who cannot go back to work, this means retirement could get ugly in a real hurry, as their finite resources are not enough to pay the bills.  They will have to live in a vacuum.

In the meantime, I think we will be making more meals at home.  It costs far, far less than eating out.  On the other hand, we are not equipped to fry oysters at home!    Sadly, only after we were finished (and stuffed with food!) did we realize we could have easily split an entree and saved a lot of money, and our waistlines.

You'll never go hungry at Rob's!

The Bitcoin See-Saw

There is a reason why Bitcoin shoots up and down in price - and not a good reason.

In recent years, the stock market has taken on the air of a carnival barker.  This is not to say that the entire game is fixed, only that there are a lot of bad bargains out there and some folks are not acting in good faith.  We've seen various scandals over the years - the Enron debacle, the Madoff scam, the 2008 blowup of mortgage-backed securities, and the various "tech" IPOs that came crashing to the ground.

In some instances, such as Enron, fraud was committed to keep the company going, when financial results were dismal.  People did odious things rather than admit failure.  In other cases, such as Madoff, it was just basic fraud - there was never any intention of running a legitimate company or even the pretense of doing so.  Just take the money and run - until they catch you.  Not a very good business plan.

The mortgage-backed securities thing was a different animal.  When people were incentivized to write as many mortgages as possible, they did.  Mortgage brokers and bankers got paid for how many loans they originated, not how many good loans they originated.   Investment bankers then bundled these loans together - good and bad - and sold them as top-rated securities, backed by real estate!  What could possibly go wrong?  Safe as houses! But as I noted before, when you create a system of rewards, people can either reap the rewards their hard work, or they can work the system to get even more rewards.  It doesn't matter what system it is, either - it could be loan origination rewards, or the production quota at the Patent Office.  Some will work hard, others will work the system.

In recent years - the last two decades or so - we've seen another animal, the "tech" IPO.  I had a front-row seat to this nonsense when I worked (briefly) at the odious large law firm.  Coming from the real world, where companies sold stock to raise capital to build factories to make widgets, and then pay dividends (you know, the "imaginary economy") I didn't understand this "new paradigm" until I figured out it was just a front for fraud.

You start a company, perhaps selling pet supplies online.  You raise venture capital and do a lot of splashy ads on television, including a multi-million dollar Superbowl "buy".  You sell pet supplies through your website for below cost, hoping to strike it big and edge out the competition.  Well, that's the theory, anyway.   Then you do an IPO, but instead of selling off 95% of the company (as Alexander Graham Bell did) you sell off 5% and keep 95% for yourself, as Martha Stewart and Facebook did. 

The purpose of the IPO isn't to raise capital to build factories, or even to buy more flashy Superbowl ads, but rather to "provide a vehicle to market shares in the company" as one prospectus boldly proclaimed.   In other words, allow the founders to cash out.  The local Ferrari dealer and the local builder of mini-mansions won't take dot-com stock in payment.

Some of these companies actually became successful.  Their model of "go big! go fast!" edged out the competition - for the most part - and early losses were later made up by wild profits.  But those examples are a minority.  What people realized is that even when they failed, these dot-com IPOs made a lot of money for the founders, the early investors, and the hangers on - including the odious law firm I was working for at the time.

Again, I was too dense to see this at the time - but the scales fell from my eyes rather quickly.  I mean, in the abstract, it makes no freaking sense whatsoever!   WillGrowCo "drops" its IPO at $25 a share.  Insiders, including the underwriter and his friends, are sold shares for $25 and immediately they are res-sold on the secondary market for $50 as the stock "pops" on the first day.  To an "old school" guy like me, this makes no sense - WillGrowCo is leaving money on the table!  They could have sold at $50 a share and raised twice as much money.  That would have bought twice as many widget factories!

But that was not the point - to raise money to build and expand. They were selling off a token amount of the company not to raise capital, but to create a market for the shares, so the founders could cash-out.  And we, the small investors of America, went along with this, whether it was Groupon, or ZipCar, or whatever.  Sure, some of us "little people" made a buck or two in the margins, if we bought at a dip and sold at a peak.  But for the most part, the insiders made scandalous amounts of money and we little people each lost a little bit.

If you could steal a dollar from every person in the United States, you'd have 330 million dollars - and likely never be caught or prosecuted.  After all, who would miss a lousy dollar?  That's the theory behind this.  "Investors" (chumps) like you and me throw $500 at some IPO using our low-cost trading platform, and we shrug our shoulders when it doesn't pan out.

Of course, these models still required some sort of business plan or product - even if it was just something as stupid as selling pet supplies online or an idiotic three-wheeled car that had no chance of ever making it into production.   Venture Capitalists sought out the tech geeks of America and pumped them for "the next big thing!" no matter how implausible it might seem.   It didn't matter if the idea was doomed to failure, they needed a "hook" to ensnare the small investors and a pretense - at least a plausible one - for the IPO.   So long as it is plausible, and you don't outright lie in the prospectus, this stuff is considered "legal."  Immoral, perhaps, but not illegal.

But then someone had a brilliant idea!  A very nasty, mean-spirited, naughty, and brilliant idea!   Why not cut to the chase and set up one of these schemes with no product or service or other idea attached to it?   Why not just sell the idea of investing itself, rather than tying it to messy factories or products or services - most of which are doomed to failure anyway?  Why spend all that money on advertisements, when the thing will advertise itself?   And why do an IPO where the SEC might take a hard look at your numbers and representations?

And thus, Bitcoin was born.   In a way, it is beautiful in its perfect evil.  No one even knows for sure who created it or who is running it or managing it - it is distributed across the globe in "mining" computers and coin "exchanges."  It is utterly unregulated, utterly untraceable, and represents nothing whatsoever.

Sure, early on, they sold this as the idea of a "currency" - that it would replace the dollar and euro and people would start buying things with their Bitcoin "wallet."  But that never happened.  A few tech companies tried to be trendy and hip by saying they accepted Bitcoin as payment.   They also claimed to be hiring minorities in order to be "diverse".   Both flashy promises, made with dramatic press releases, are later quietly forgotten, of course. One by one, the companies claiming to accept Bitcoin have dropped out of the coinverse - if they were ever in it.  Even the Bitcoin convention in Miami didn't accept Bitcoin as payment.

And it isn't hard to see why.  Simple transactions could take several minutes, early on, and as the system gets older and older, the transaction times increased to the point now where it can be an hour to consummate a transaction.  And the costs - once touted as free - are turning out to be in the tens, then hundreds of dollars.  Old-fashioned wire transfers are turning out to be faster and cheaper.

The only "real" use has been as ransom payment or for other illegal things, such as selling drugs, guns, or children, and transferring money to odious people (terrorists, for example) across the globe.  How long before governments shut that down?  And they can shut it down, not by outlawing Bitcoin, but by severely regulating the "exchanges" to the point where you would have a hard time getting your money out.  China already seems poised to do this.

The other thing that has hindered Bitcoin is the volatility. While in general its price has steadily increased over time, in any given year, it can go up and down by 50% or more - usually within days, which can result in huge losses if you consummate a transaction in Bitcoin and fail to take your proceeds out in local currency quickly.

Since Bitcoin hasn't worked well as a legitimate currency, proponents - and there are many, usually people who own a lot of coins or who are paid by people who own a lot of coins - are selling Bitcoin as a "virtual investment" - an investment in nothing or basically investing in scarcity itself.   "This thing we created is scarce.  It has no use, and you can't even see or touch it, but since it is scarce, it is valuable!"  It takes Gold-buggery to its logical conclusion.

But recently, Bitcoin shot up to over $60,000 a "coin" and then dropped to $30,000 a "coin" within a very short period of time.  What happened?  Some blame Musk for pumping up the value by making specious announcements that Tesla will accept Bitcoin as payment - and then quickly backtracking.  Musk got in trouble for pumping Tesla stock - the SEC regulates that!  But Bitcoin?  You can pump-and-dump all day long and its perfectly legal.

I suspect, however, that the volatility of Bitcoin is inherent in its design and is by design.  It is a See-Saw where the insiders who own most of the coin (by some accounts, only about 1,000 people) wait for one of these "peaks" in price and then wisely sell some of their "coins" to cash in on the deal.  The insiders flood the market a bit, so supply exceeds demand, and the price plummets.  They wait a few more months and plant some more stories in the "financial press" about how Bitcoin is going to hit a billion-bazillion-trillion dollars, and wait for the price to go up again - and the process repeats.  Up, Down, Up, Down.  See, Saw, See, Saw.  It is predictable.

Think of it this way.  I mentioned before how "Market Cap" is utter nonsense.  Bill Gates is "The Richest Man In The World(tm)" or was at one time, because of the cumulative value of all his Microsoft stock.  But as I pointed out, this "Market Cap" number is merely what the last chump paid for a share of that stock.  It doesn't represent the value of the company in most cases.   Sure, once in a while a company is bought out by another, when it is undervalued.  But these sky-high valuations of Apple, Microsoft, Facebook, Linked-In or whatever, are often irrational numbers.

If Gates decided to "sell out" and put all his Microsoft shares up for sale in a "Market" sell order, the price would plummet.   Not only would people wonder why he was selling (what does he know?) but there would not be enough people to buy up all those shares.  Supply would exceed demand by a factor of ten, and the price would drop to nothing.  It is how I bought Avis stock for 74 cents a share - people dumped the stock when bankruptcy rumors were floated.  Few bought.

Supply and demand determine prices far more than actual value.

Bill Gates - and Zuckerberg and Musk and the rest of them have sold shares of their company's stock, in order to pay their bills and buy fancy houses and whatnot.   But they smartly sell off only a small portion at a time, regularly, and thus not depress the price of their investment.  In IPO situations, there is often a "lockout" period to prevent insiders - or at least some insiders - from cashing out too soon.  Usually the employees paid in stock options are locked out, but the real players are not.   Yea, act shocked.

With Bitcoin, the same is true, but there is no hierarchy or organization or lockout period to prevent panic selling of the coin.  This sort of is like a version of the prisoner's dilemma - you can sell your Bitcoin when it hits an all-time high, but by doing so, you depress the price of the coin, and thus damage your fellow coin-owners investment and any remaining investment you have.   Perhaps it is more akin to a cartel like OPEC, where if everyone obeys the rules and only sells a little oil at a time, they can get really high prices for the oil and make more money.   But if one person cheats, the whole deal is off.   And what we learned in economics (and real life) is that cartels eventually break down, as OPEC has, again and again, as each nation cheats on the other.

And in the past, there have been events where someone "accidentally" sold off a huge chunk of Bitcoin and caused the price to plummet in a matter of minutes, because despite all the hype, it  actually is pretty thinly traded.  The price recovered in a matter of hours, but it illustrates how one big "sell" order can cause the price to drop dramatically.  It explains why the price has dropped in recent weeks - someone is selling off their hoard, or a good portion of it.

Some folks would look at the price chart above and say, "Well, look, overall the price has gone up, up, up!  There have merely been some adjustments here and there!"   But if you look at the smaller peaks and valleys, and blow them up, they look exactly like the recent peak and crash.  The dollar amount of price make no real difference. If you "invested" $5000 in Bitcoin at $18,000 a "coin" in December of 2017, and then sold it for $3300 a "coin" in December 2018, you lost most of your money - like 4/5th of it.  That "smaller" peak-and-valley represents an even greater loss than the recent 50% price drop.

It just seems smaller when you look at the larger chart and the previous gains and losses look more like system noise than signal.

But the question remains - will Bitcoin go up in value?  And will it crash yet again?   See.  Saw.  See.  Saw.  You can kind of bank on it.  But eventually, there will have to be some "there" there for Bitcoin.  In the case of ZipCar, it was eventually bought out by Avis.  There was some underlying value in the company, although a lot less than the vaunted "Market Cap" after the IPO.  Where did all that equity evaporate to?  It never existed, of course.

My take on it?   Each successive pop (or bubble) in the price of Bitcoin will be harder and harder to achieve.  If you google Bitcoin, you will get "hits" for tons of articles by "professional analysts" who say it will hit $100,000 a coin or even a million dollars a coin.  When you read these articles, the "logic" they present amounts to, "I just said it would, can't you read?  Are you stupid or something?"   And that is about the extent of the reasoning, as unlike traditional investments, which can be quantified by rate of return, retained earnings, or dividend ratio or even liquidation value, there is no real way to quantify Bitcoin, as it is an investment in scarcity itself.

There is a distinct possibility that eventually even the insiders will tire of this game and walk away. They will pump and dump and try to maximize the realization of their outcome by selling off their coins in dribs and drabs, until there is no one left to buy the damn things.  Or maybe one day, people will wake up and say, what the heck were we thinking?  Investing in nothing whatsoever?  What drugs were we taking when we believed this "virtual gold" nonsense?

Maybe. But I doubt it. A more likely scenario is that like a child with a shiny new toy, the small investor will be distracted by a newer, shinier toy, and discard Bitcoin in the sandbox as just another passing fancy.  A fad.  A trend.

We'll just have to wait and see.  Personally, I would not touch this nonsense with a ten-foot pole.  While others (a very few people) will make tons of money off it, the rest of us - including me - would lose a little - or a lot.

Mr. Madoff - you had the right idea, just the wrong vehicle for it!